
How Much Revenue Does a Bad Online Reputation Actually Cost a Business?
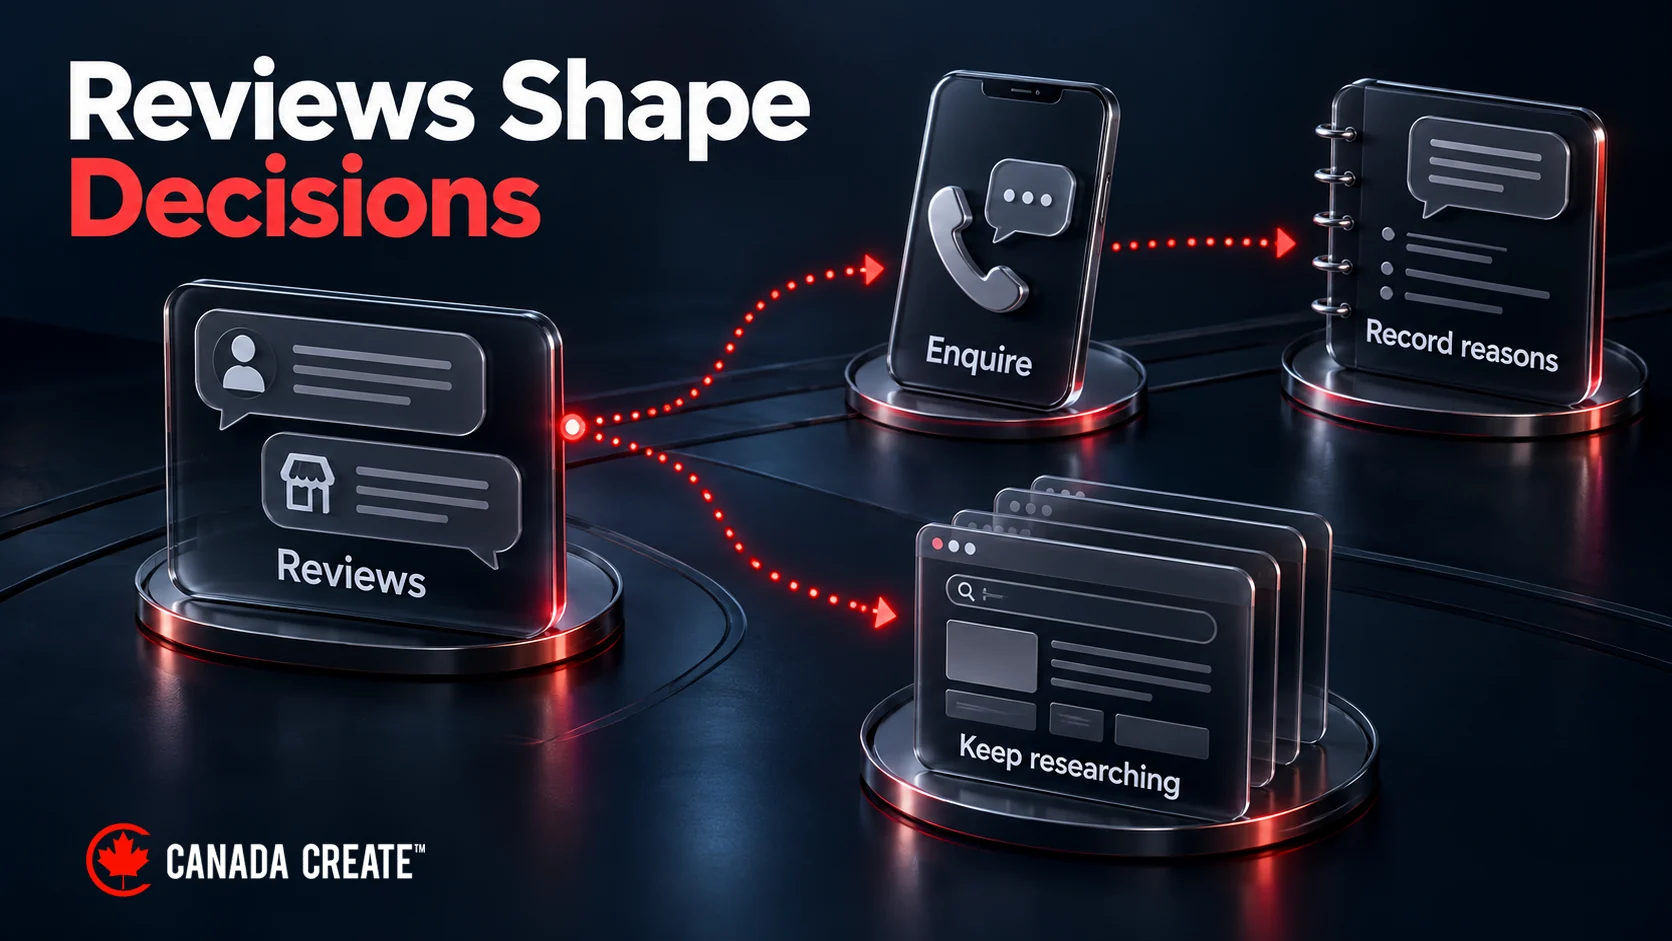
A bad online reputation can put revenue at risk when it changes whether a suitable customer contacts you, accepts a quote or buys again. Estimating that cost comes before comparing reputation management services or hiring an online reputation management company. There is no defensible universal percentage to apply to every business. A rating change alone cannot tell you how many sales you lost, and a complaint is not proof that every reader chose a competitor.
The useful question is narrower: which customer decisions can you document, what might those decisions be worth, and which service or communication problem can you correct? This guide shows how to separate recorded losses from planning scenarios, calculate a financial range from your own inputs, and decide what deserves attention first. All numerical examples below are hypothetical calculations, not Canada Create client results or forecasts.
If you are deciding whether to budget for ongoing help, estimate the problem before choosing a solution. The scope of an ongoing program is covered separately in Brand Reputation Management. Here, the focus is the business cost and the evidence needed to assess it.
Why This Comes Up Before a Bigger Decision
A fall in calls, a prospect mentioning a review or a recurring complaint can make reputation feel like the obvious explanation for weaker sales. It may be part of the explanation, but the timing alone is not enough. A price increase, reduced advertising, a seasonal lull, unavailable appointments or an unanswered phone can produce the same visible outcome.
Investigating first helps avoid two expensive mistakes. One is dismissing a repeated service problem because the overall rating still looks acceptable. The other is buying a large reputation program when the immediate problem is a broken booking form or a sales backlog. Record what changed, when it changed and which part of the customer journey is affected before deciding what to fund.
Do not postpone a necessary service correction while waiting for perfect attribution. If customers are repeatedly receiving the wrong information, correct it. The financial investigation determines how to evaluate the response, not whether a verified problem deserves to be fixed.
Where Reputation Can Affect the Revenue Path
Online reputation is broader than the average rating on one profile. A buyer may encounter review text, the business’s replies, a search result, an unresolved complaint or inconsistent information across listings. These surfaces can raise questions about reliability, suitability, quality or the effort needed to resolve a problem.
| Decision point | Possible business effect | Evidence to collect |
|---|---|---|
| Before an enquiry | A suitable prospect may keep researching rather than contact the business. | Comparable profile interactions, website visits and qualified enquiries, with changes in demand and traffic recorded. |
| During a sales conversation | A prospect may ask for reassurance, delay a decision or decline. | The prospect’s stated concern, quote stage, final outcome and other reasons given. |
| After a purchase | An unresolved issue may lead to a refund, extra service work or no repeat purchase. | Actual refunds, labour, follow-up outcomes and repeat purchases where records can be linked appropriately. |
| Across the operating team | Staff may spend time investigating and resolving repeated complaints. | Time spent by activity, recurring causes and the cost of preventing recurrence. |
We help businesses earn more genuine reviews and respond to every review professionally.
These are possible pathways, not additive percentages. A single customer could appear in several rows. Counting the same cancelled order as lost revenue, a lost sale and a refund would overstate the effect. Establish one financial treatment for each event before adding up the totals.
The Signals That Tell You It Is Time to Act
Use specific patterns to prioritize investigation rather than treating a particular star rating or number of days as a universal danger threshold:
- Your sales or intake team hears a repeated, identifiable concern. Record the issue in the prospect’s own words where practical. Distinguish “I saw a review about missed appointments” from a salesperson’s assumption that reviews caused a rejection.
- Recent reviews describe the same preventable service problem. Several reports about unclear pricing or missed updates are a reason to inspect that process. Check the underlying records rather than assuming either the customer or the business account is complete.
- Important complaints have no clear owner or follow-up. An unanswered review is not a measurable lost sale by itself. It is a prompt to check whether the business investigated the concern and whether an appropriate public response is missing.
- Enquiry or sales patterns change alongside review concerns. Compare the same channel, offer, location and type of customer where possible. A change in the overall average can conceal a different traffic mix.
- Your visible feedback no longer reflects the current service. Old complaints may describe a problem that has been corrected, or recent complaints may reveal a new one. Date the operational changes and assess recent feedback without suppressing legitimate criticism.
A lower average rating and stalled review volume can be useful context. Neither proves a revenue loss, and neither creates a universal rule about which businesses customers will consider. Read the substance, recency and relevance of the feedback alongside your records.
Start With Three Separate Financial Buckets
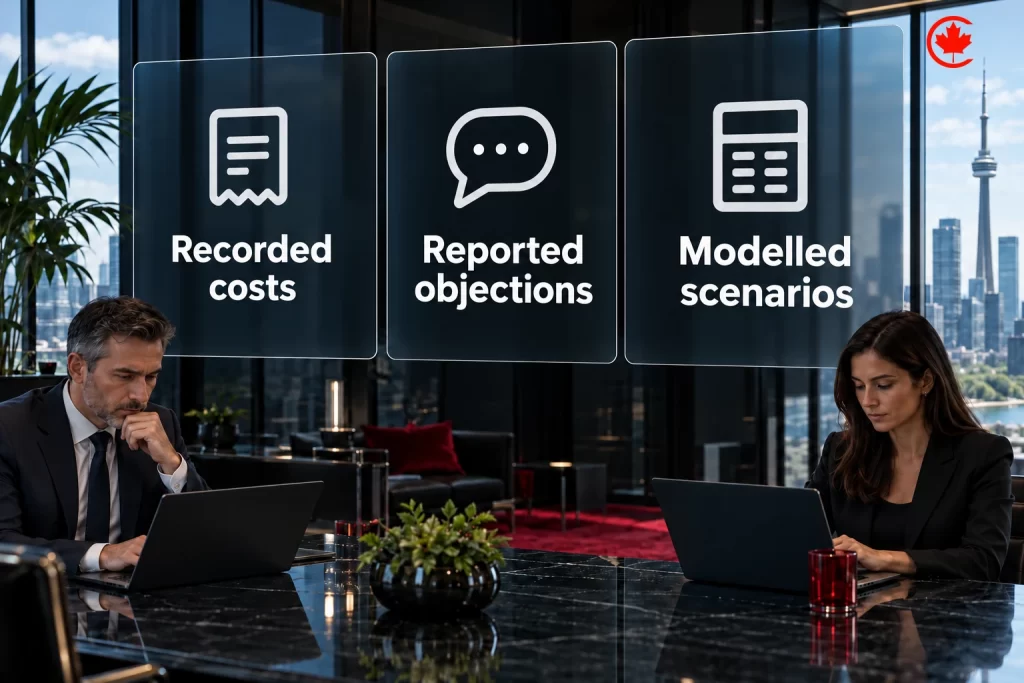
1. Recorded costs and completed outcomes
Use actual business records for refunds, credits, documented rework and complaint-handling time. Label them precisely. A refund is a recorded financial event; the claim that an online review caused it needs separate evidence. The underlying service failure may have caused both the refund and the review.
For sales, distinguish an accepted order that was cancelled from a quote that never became an order. A cancelled order has a specific value, but the net effect still depends on refunds, recovered stock, avoided delivery costs and replacement work. An unaccepted quote is an opportunity, not revenue that was already earned.
2. Reported review-related lost opportunities
A prospect may explicitly say a review influenced the decision not to proceed. That is valuable evidence of a reported objection. Record it as such, including whether price, availability or another issue also mattered. Do not automatically assign the entire quote value to reputation or assume the business would otherwise have won.
If you estimate the expected value of those opportunities, use a relevant historical close rate and explain the assumption. Deals at an early enquiry stage should not be valued as though they had already passed qualification and accepted a proposal.
3. Unobserved decisions modelled for planning
You will not know every person who read a review and never contacted you. A model can show what different enquiry shortfalls would mean financially, but it cannot count those people or establish why they left. Keep that scenario separate from recorded sales, and never present it as a measured maximum loss.
This distinction lets an owner act without pretending to have certainty. Recorded costs show what has happened. Reported objections identify a plausible issue. Scenarios test whether a potential problem would be material enough to investigate.
How to Estimate the Revenue at Risk
For a lead-generation business, a simple planning calculation is:
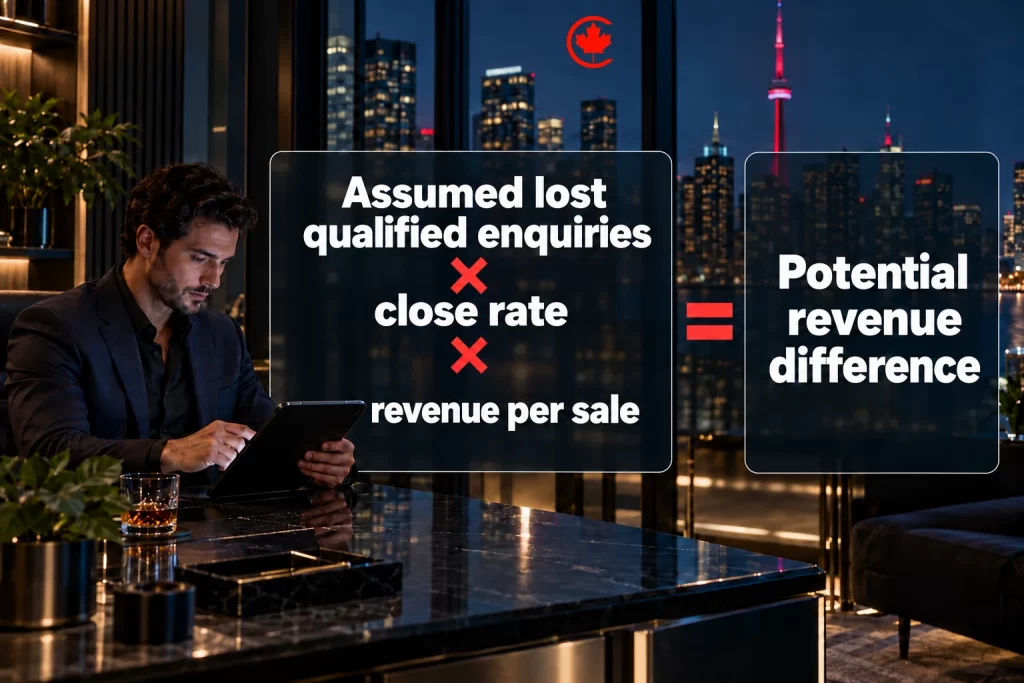
Potential revenue difference = assumed lost qualified enquiries × expected close rate × average revenue per completed sale.
Use the close rate for the same kind of enquiry and the same stage of the sales process. If the business wins one in four qualified enquiries, use that rate for qualified enquiries, not for every website visit or spam form submission. Choose a revenue value that reflects the offer being assessed rather than the largest sale the business has ever made.
For an online store, the comparable calculation is assumed lost orders multiplied by average net order revenue. Account for cancellations, returns and discounts consistently. For recurring services, start with a clearly defined period. Do not multiply a missed first purchase by an assumed lifetime value unless you have retention and margin records that support that projection.
A tangible example with explicit assumptions
Suppose a service business is assessing a possible monthly shortfall of five qualified enquiries. Assume its relevant close rate is 40%, its average completed sale is C$1,500 and the contribution margin on that work is 40%. These are illustrative inputs, not industry averages:
- Five enquiries × 40% close rate = two expected sales.
- Two sales × C$1,500 = C$3,000 in potential monthly revenue.
- C$3,000 × 40% contribution margin = C$1,200 in potential contribution before any extra fixed or program costs.
Under those assumptions, failing to address a problem that genuinely costs five qualified enquiries could mean C$3,000 less revenue in that month. The calculation does not prove that reputation caused the shortfall or that a response program will recover it. Change the assumed enquiry loss or the actual economics and the answer changes.
Show sensitivity rather than a dramatic “up to” claim
The table below uses the same C$1,500 sale value, 40% close rate and 40% contribution margin. The enquiry counts are alternative planning assumptions, not observed losses or a predicted range.
| Assumed qualified enquiries lost in one month | Expected sales difference | Potential revenue difference | Potential contribution difference |
|---|---|---|---|
| 0 | 0 | C$0 | C$0 |
| 2 | 0.8 | C$1,200 | C$480 |
| 5 | 2 | C$3,000 | C$1,200 |
| 10 | 4 | C$6,000 | C$2,400 |
The fractional sale in the second row is an expected value across similar opportunities, not part of an actual sale. C$6,000 is not the maximum that a poor reputation can cost a business. It is simply the result of the largest input shown here. Use your own defensible inputs and include a zero-effect case when the effect is unknown.
Revenue Is Not the Same as Profit or Recoverable Value
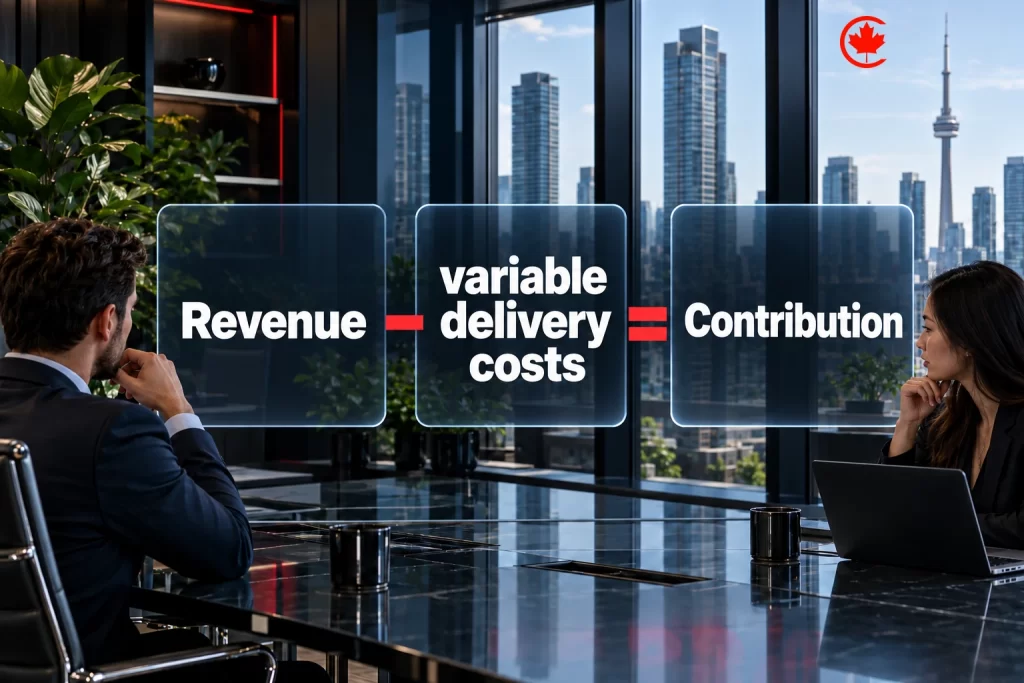
Recovering a C$1,500 sale does not create C$1,500 of profit. Materials, labour directly needed for delivery, payment costs and other variable costs may consume part of the revenue. Capacity matters too: if the team cannot fulfil additional work without overtime or new resources, the incremental economics can be different.
For a budget decision, contribution is often more useful than headline revenue. Use an explicit definition, such as revenue minus the costs that would arise from delivering the additional work. Then deduct the incremental cost of the proposed response. Your accounting treatment may differ, so keep the calculation consistent with the records used to manage the business.
For example, assume a proposed monitoring and follow-up process costs C$600 per month and each additional completed sale contributes C$300 after its variable costs. Two additional sales would cover that monthly process cost. That is a break-even calculation, not evidence that the process will generate two sales, a market price for reputation services or a recommendation to spend C$600.
Include staff time even when no new invoice arrives. If eight hours are redirected from paid delivery or sales follow-up to resolving complaints, the trade-off is real. But do not count both the same wages and the entire value of hypothetical displaced work as separate cash expenses without explaining what each number represents.
Build a Baseline That Can Answer the Question
A useful baseline connects feedback to business activity. A screenshot of the rating is not enough. Choose a review period that fits the sales cycle and produces enough enquiries to be informative. Retain earlier periods for context, but do not assume that matching calendar months removes every difference between them.
For each location or offer being assessed, record:
- The platform, observation date, average rating, review count and recurring themes.
- The channels bringing enquiries, with qualified and unqualified contacts separated.
- The number of quotes, completed sales, cancellations and refunds using consistent definitions.
- Review-related objections, including the stage, stated reason and final outcome.
- Response ownership, service fixes and the dates those changes were implemented.
- Changes in advertising, pricing, availability, staffing and offers that could affect the comparison.
Keep the working log proportionate. A small business can start with a simple set of fields rather than a complex attribution system. Use an internal enquiry reference, the date, the relevant concern category and the outcome. Avoid copying unnecessary personal details into a broad marketing spreadsheet, particularly when the service involves confidential matters.
Review the definitions with sales and reception staff. If one person labels every unanswered quote “reputation” and another only uses that label after a direct statement from the prospect, the totals are not comparable. Allow “unknown” and multiple stated reasons instead of forcing every lost opportunity into one explanation.
What the Numbers Can and Cannot Establish
A rise in enquiries after a review-response initiative is encouraging, but a before-and-after comparison does not isolate its effect. Demand may have increased, an advertising campaign may have improved or appointment availability may have opened up. Report the change, list those other factors and avoid a causal claim the design cannot support.
Comparing similar channels and offers can make the analysis more useful. For instance, inspect qualified enquiries from the same source separately from overall website traffic. A greater share of low-intent visits can reduce the overall conversion rate while the rate for an important customer group stays stable. The reverse can also happen.
Review-related complaints are also a selected sample. People who contact the business and explain their concerns are not necessarily representative of people who leave silently. Likewise, a rise in review volume may reflect a newly introduced request process rather than an improvement in service. Describe both the outcome and how the evidence was collected.
Do not promise that reaching a chosen star rating will recover a fixed amount of revenue. Different buyers weigh different issues. A detailed complaint about a risk relevant to the purchase may matter differently from a low rating without context. The point of monitoring is to understand and address those concerns, not to turn one public number into a guaranteed sales forecast.
Mistakes to Avoid When Assessing Reputation Costs
A reactive approach can leave the underlying issue untouched. Posting a polished response to a complaint about missed updates will not fix a process in which no one owns customer updates. Connect recurring feedback to an operational action, an accountable person and a check that the correction is working.
Another mistake is treating every negative review as removable. Disagreement with the opinion does not establish a policy violation. Preserve the relevant evidence and use the platform’s reporting process when there is a genuine policy basis. Do not promise a customer or colleague that a legitimate complaint will disappear. Google limits review removal to policy-violating content, not reviews a business simply dislikes.
Review requests also need to follow the platform’s rules. Where requests are permitted, ask for honest feedback without incentives or selecting only customers expected to respond positively. Do not make compensation for a service problem conditional on editing or removing a review. Check the applicable platform guidance before implementing a request workflow. For Google specifically, its review-contribution policy prohibits incentives and selectively soliciting positive reviews; it permits genuine, unincentivized requests without influencing the rating or content.
Finally, separate responding publicly from resolving privately. A reply should acknowledge the concern and explain an appropriate next step without exposing private customer details. In sensitive services, even confirming a person’s customer relationship can create a problem. A public argument about the complete transaction history can make the situation worse rather than establish trust. Google’s guidance for review replies recommends professional responses and protecting private information.
A Practical Framework or Checklist
| Step | What you do | Why it matters for revenue |
|---|---|---|
| 1. Establish your current baseline | Pull average rating and review count across all major platforms, alongside enquiry and sales records. | Creates a dated starting point without equating the rating to revenue. |
| 2. Track lost-deal reasons | Ask sales or intake staff to log when a prospect mentions reviews and record other stated reasons. | Separates reported concerns from assumptions about lost opportunities. |
| 3. Set a realistic review-response target | Name an owner, review privacy concerns and personalize the response. | Provides a consistent way to address concerns without promising a sales effect. |
| 4. Build an active review generation habit | Request honest reviews consistently only where the platform permits requests. | Creates a repeatable feedback process and can reveal service issues. |
| 5. Recheck the baseline quarterly | Compare rating, volume and lost-deal mentions against the original baseline; inspect urgent issues sooner. | Shows changes to investigate alongside sales and other business factors. |
The quarterly review is an operating checkpoint, not a promised recovery window. A recurring service failure may require immediate attention. A long sales cycle may require more time before completed-sale outcomes are available. Choose response targets that the team can meet and keep the financial evaluation separate from the urgency of helping a customer.
Decide What to Fix First
Correct a verified service failure
When repeated feedback matches internal records, address the process creating the complaint. Examples include unclear approval steps, missed appointment confirmations or invoices that do not match the agreed scope. Define what will change and how the business will know it has changed. Do not treat a new review request campaign as a substitute for that correction.
Resolve unclear or inconsistent information
If customers are arriving with the wrong expectations, compare the website, quotes, booking confirmations and profile information. Make the actual limitations and next steps clear. A better explanation may improve suitability rather than increase the raw number of enquiries, which can still be a useful outcome.
Investigate a suspected policy violation
Keep the review URL, date and relevant supporting record, then assess the applicable platform policy. A report is a request for platform review, not a guaranteed removal. Avoid public speculation about the reviewer’s identity or motives, and do not expose private records to defend the business.
Do not default to a reputation explanation
If enquiries fall without review-related evidence, test the basics. Are calls answered, forms delivered, products available and campaigns still running as intended? A reputation investigation should sit beside those checks, not replace them. Keep the cause marked unknown until the available evidence supports a more specific conclusion.
How to Evaluate an In-House Process or Outside Help
The decision depends on workload, risk and accountability, not just the current rating. A single-location business with modest review activity may be able to assign monitoring and escalation internally. A more complex operation may need coordinated access, response review and consistent reporting across teams.
Evaluate the proposed work against concrete deliverables:
- Who checks each relevant platform and who can approve a response?
- How are urgent complaints, confidential matters and disputed facts escalated?
- Does the process connect recurring feedback to an operational fix?
- Are requests compliant with each platform, and can the workflow be reviewed?
- Does reporting distinguish actions completed, customer outcomes and uncertain revenue estimates?
- What staff time, software cost and outside fees are included, and what is excluded?
Be cautious about offers framed around guaranteed star ratings, guaranteed deletion or an unsupported revenue recovery percentage. Ask to see how performance will be measured against your own baseline. A useful report should be able to say that the commercial effect is still unclear rather than manufacture a return on investment from a rising rating.
Check Paid Acquisition Costs Without Counting the Same Loss Twice
A reputation concern may become visible while reviewing advertising performance. The distinction to preserve is between what it cost to attract attention and what happened after that attention reached the business. A higher cost per enquiry is an observed efficiency change; it does not identify the cause on its own.
For a hypothetical comparison, assume an advertising campaign spends C$1,000 in each of two periods. In the first, it generates 50 qualified enquiries, so cost per qualified enquiry is C$20. In the second, it generates 40, so that cost is C$25. Assume the qualification definition is unchanged. The arithmetic shows a C$5 increase per qualified enquiry, or 25% relative to the first period.
That does not prove reviews caused the change. The auction may have become more expensive, the advertisement may have reached a different audience, the landing page may have changed or the business may have had fewer appointments available. Inspect clicks, relevant visits, enquiry quality and stated objections before assigning a reputation explanation.
Nor should the business automatically add the whole C$1,000 advertising spend to a model of lost revenue. The campaign still produced enquiries, and the spending may already be part of the normal acquisition cost. If a financial model counts both acquisition expense and missed contribution, define the comparison carefully so that the same effect is not counted twice.
A useful next step is to compare the same offer and channel using consistent qualified-enquiry criteria. Keep a note of advertising changes and ask whether prospects who raised review concerns were actually exposed to the same customer experience. This can narrow the investigation without pretending that advertising analytics reveal the private reason for every decision.
Assess Discounting and Price Pressure Separately
A prospect may cite a negative review while asking for reassurance or a lower price. Record what was said and the commercial decision made. Do not assume the review caused the entire discount: the buyer may also be comparing prices, negotiating normally or responding to another concern.
Discounts affect revenue and contribution differently. Suppose a hypothetical job sells for C$1,000 and has C$600 in variable delivery costs. Its contribution is C$400. A C$100 discount reduces revenue to C$900 and contribution to C$300 if those delivery costs stay unchanged. That is a 10% reduction in selling price but a 25% reduction in contribution.
This example does not establish a typical reputation penalty or recommend refusing every discount. It shows why a business should record the actual concession and its reason rather than track only whether the deal closed. The value of keeping a suitable customer may still justify a decision, but the cost should be visible.
When the concern is a specific service risk, consider whether a clear explanation or a verifiable process improvement addresses it more directly than a price concession. Do not invent guarantees, credentials or outcomes to reassure the prospect. If the business cannot meet the requested conditions, be clear about that limit instead of turning a sales objection into a future service complaint.
Build a Complaint Record That Leads to a Useful Decision
Use separate fields for the public feedback, the internal investigation and the commercial outcome. Mixing them together makes it easy for an allegation to become an accepted fact or for a response to be mistaken for a resolution.
The feedback record can include the platform, review link, date, theme and whether a response is required. The investigation record can identify the responsible person, the relevant service process and the facts that have been checked. The commercial record can note a refund, replacement work, an open opportunity or a completed sale, with the date and value where appropriate.
Give each issue a status that means something operationally: awaiting information, under review, action agreed, action completed or no further action justified. “Replied” should not automatically mean “resolved.” A courteous public response may be appropriate while a customer issue still needs private follow-through.
For example, a complaint about an unclear delivery date could lead to three different findings. The confirmation may have stated the wrong date, the delivery team may have missed a correct commitment, or the records may not establish what was communicated. Each finding calls for a different action. A generic apology and another review request would not distinguish them.
Keep access appropriate to the information involved. A person drafting a public reply may need the approved explanation and next step, not the customer’s full file. Record enough to support the decision without copying confidential details into a widely shared reporting document.
Choose the Right Level of Response
Not every negative comment needs the same process. A routine complaint with a clear service fix, an uncertain account of events and a serious allegation require different levels of internal review. Prioritize based on potential customer harm, the facts available, repeated patterns and who has authority to act, rather than the most dramatic wording alone.
For a straightforward issue, confirm the facts, assign the correction and provide a concise public next step when appropriate. For an unresolved dispute, do not fill gaps with speculation. Acknowledge what can safely be acknowledged and move the detailed discussion to a suitable private channel.
If the matter involves potential safety, confidentiality or legal consequences, route it to the appropriate responsible person before publishing a detailed explanation. This guide is a commercial assessment framework, not a determination of legal liability. Avoid admissions or accusations that the available records do not support.
The response decision and the financial estimate should remain separate. A complaint can deserve immediate attention even when no lost sale can be measured. Equally, a dramatic hypothetical revenue figure does not justify misleading replies, pressure on the reviewer or disclosure of private information.
What a Useful Review Meeting Should Decide
A recurring review should end with decisions, not just a rating screenshot. Start with unresolved customer issues and repeated service themes. Check whether previously agreed actions happened and whether the same problem is still appearing in verified records.
Then inspect the commercial measures with their limitations visible. Are qualified enquiries changing within comparable channels? Are review-related objections recurring? Have enough sales matured to assess outcomes? Did pricing, staffing, campaigns or availability change at the same time? Keep “not yet known” as a legitimate answer.
Choose a next action for each material finding. Continue a process that is functioning, revise one that is not addressing the cause, investigate a new issue or stop an activity that has no clear purpose. Assign responsibility and record what evidence would change that decision.
If the rating improves but the recurring service problem remains, do not call the underlying issue solved. If service complaints fall but revenue has not moved, acknowledge the operational improvement without manufacturing a sales return. A responsible program can produce useful learning and better customer handling even while its incremental revenue effect remains uncertain.
Adapt the Calculation to the Way Your Business Earns Revenue
Appointment-based services
Distinguish an enquiry, a booked appointment and an attended appointment. A reputation concern might affect the first decision, while limited availability or a missed reminder affects a later one. If the calendar is already full, more enquiries may not create more revenue unless the business can provide additional suitable appointments.
Use the contribution from completed work rather than the advertised appointment price alone. If an appointment is cancelled, check whether the slot was filled by another customer. Counting the cancelled booking’s full value as lost revenue would overstate the effect when replacement work took its place.
Online stores and repeat purchases
Separate a missed order from a returned order. A missed order is usually an estimate unless the customer states the reason; a returned order is a recorded event with its own costs and recovery. Stock, shipping delays, price and product suitability can affect both reviews and purchase decisions.
For repeat purchases, compare customers with similar opportunities to buy again. Someone who has not returned may not yet need the product. Do not classify every inactive customer as lost to reputation or apply an assumed lifetime value to everyone who encountered a negative review.
High-value quotes and longer sales cycles
For project work, a small number of opportunities can make monthly totals volatile. One unusually large quote can dominate a theoretical loss calculation even though its chance of closing was uncertain. Use stage-appropriate assumptions and separate the largest opportunity from the typical offer.
Allow enough time to distinguish delayed decisions from closed-lost outcomes. Record the next expected decision date and whether the prospect actually declined. A business can address a stated reputation concern promptly without pretending that an open proposal is already lost revenue.
Multiple locations or service teams
Keep the customer-facing unit clear. A complaint about one location may identify a local issue, a company-wide process problem or a misunderstanding. Compare location-specific feedback and outcomes before assigning the same effect to every branch.
Common definitions make comparison possible, but they do not make every location equivalent. Different offers, catchments, staffing and availability can affect results. A company-wide average can hide a serious recurring issue at one site or create a misleading impression that every team needs the same intervention.
A Worked Investigation: Separate the Shortfall From Its Cause
Consider a hypothetical business comparing two periods. In the earlier period, it recorded 100 qualified enquiries and 40 completed sales. In the later period, it recorded 80 qualified enquiries and 32 sales. Assume the definitions and sales-maturity window are consistent. The close rate is 40% in both periods, while enquiries and sales are each 20% lower.
If average sale revenue stayed at C$1,500, the eight-sale difference represents C$12,000 less recorded revenue. That describes the comparison. It does not establish C$12,000 lost because of reviews. To investigate the cause, check whether advertising exposure, relevant demand, availability, pricing or service capacity changed.
Now suppose three prospects in the later period explicitly mentioned a review concern. That gives the team three reported concerns to investigate, not proof that the 20-enquiry shortfall was caused by reputation. Some prospects who mentioned reviews may still have purchased. Others may have had several reasons for declining.
A responsible summary would distinguish the facts: “Sales revenue was lower across these periods; three prospects mentioned review concerns; the contribution of reputation to the overall change is not isolated.” The next action is to resolve the verified concern and improve the records, not to publish a causal loss percentage.
This distinction is practical rather than academic. If advertising was paused, a reputation program alone cannot be expected to restore the missing visits. If the same complaint is repeatedly blocking otherwise suitable prospects, correcting that issue may deserve priority even before its full financial effect can be quantified.
Keep Program Cost Separate From the Cost of Reputation Damage
“What does a poor reputation cost?” and “What does reputation management cost?” are different buying questions. The first concerns business outcomes and uncertainty. The second concerns the work purchased, who performs it and the terms. A provider’s fee does not establish the size of your loss, and a large theoretical loss does not justify every proposed fee.
For an internal budget, separate one-time work from recurring work. Initial investigation, a response workflow and staff training are different from ongoing monitoring, review handling and reporting. Include any service correction that sits outside the communications work, such as improving appointment updates or clarifying the quoting process.
Assess each proposed activity against the problem found. If the main issue is inconsistent customer updates, paying for more monitoring without changing that process may identify the same complaint repeatedly. If the process is corrected but feedback is spread across many profiles, coordinated monitoring and ownership may be the more useful next step.
Set a review point and a decision rule before spending. For example, the team may first assess whether responses are handled consistently and the recurring service issue has stopped appearing in verified cases. Later, it can assess enquiry quality and completed sales. Those are staged evaluation questions, not a commitment that revenue will recover within a particular quarter.
Use a Short Owner’s Worksheet Before Approving a Budget
Write down the answer to six questions. Missing answers are useful: they show where an estimate is still an assumption rather than a result.
- What changed? Record the dates, affected offer or location and the specific customer concern.
- What is directly known? List completed outcomes, actual refunds or rework, and review-related statements without assigning a cause beyond the evidence.
- What is only assumed? Identify any proposed enquiry shortfall, close rate, sale value and margin used in a scenario.
- What else could explain the pattern? Record changes in demand, traffic, pricing, availability and operations.
- What action addresses the verified issue? Assign an owner, a practical scope and a way to confirm the action occurred.
- What would justify continuing or changing the approach? Name the operational and commercial outcomes to inspect, with enough time for those outcomes to mature.
Use this worksheet to challenge an estimate in both directions. A large-looking number may depend on unrealistic assumptions. A small-looking number may omit repeated labour or a high-value opportunity that deserves separate attention. The aim is a defensible decision, not the biggest possible loss figure.
Reviews, replies and profile accuracy are managed together in our local SEO services in Toronto.
When You Are Ready for the Full Program
Start with one clear output: a dated baseline, a short list of verified service issues and a financial model whose assumptions are visible. That gives you a better basis for deciding whether to improve an internal process or seek ongoing help.
The ongoing service scope is explained in Brand Reputation Management. Use the review monitoring checklist above to identify the work your team can own. For the separate question of challenging a review, see what actually counts as a fake Google review worth disputing.
Frequently asked questions
What does online reputation management cover when a business suspects reviews are costing it sales?
It covers every place a buyer forms an opinion of you, which is wider than the average star rating on one profile. That includes review text, your replies, search results, unresolved complaints and listings that give conflicting details. Each of these can raise doubts about reliability or about how hard it would be to fix a problem. Managing them means correcting verified service issues, answering complaints properly and keeping business information consistent.
How should I weigh what online reputation management costs against the revenue a bad reputation puts at risk?
Estimate the revenue at risk from your own records first, then compare that range with the written quote for any program. Keep the two figures apart, because the fee for a program is a different number from the cost of the damage. If a broken booking form or a sales backlog is the real cause, a large reputation program will not fix it. Start with the problem you can verify.
How can social media posts and public complaints hurt a brand's reputation and sales?
A complaint that buyers can read publicly may lead a suitable prospect to keep researching instead of getting in touch. During a sales conversation, the same post can prompt a request for reassurance, a delay or a refusal. Silence on an important complaint matters too, since readers can see when nobody has followed up. Record the concern in the prospect's own words so you can tell an actual objection from a guess.
What formula estimates the revenue a poor online reputation could be costing my business?
For a business that runs on enquiries, multiply the assumed number of lost qualified enquiries by your close rate for that kind of enquiry, then by the average revenue per completed sale. An online store multiplies assumed lost orders by average net order revenue, treating returns and discounts consistently. The post's own example uses five enquiries, a 40% close rate and a C$1,500 sale to reach C$3,000 for one month. The answer is a planning scenario and does not prove reviews caused the shortfall.
Is revenue lost to bad reviews the same as lost profit?
No, and treating them as equal overstates the damage. Winning back a C$1,500 sale does not add C$1,500 of profit, since materials, delivery labour, payment fees and other variable costs take part of it. Capacity also matters if extra work would need overtime or new staff. For a budget decision, contribution (revenue minus the costs that rise with each sale) is usually the more useful figure.
What are examples of real costs a bad online reputation can create?
Recorded costs include refunds, credits, documented rework and the staff time spent handling complaints. A second group covers prospects who said outright that a review put them off, which is useful evidence but not proof that the whole quote was lost. A third group is modelled scenarios for people who read reviews and never called, which you cannot count directly. Keeping these three groups apart stops one cancelled order from being counted three times.
Should the cost of a reputation program be counted against revenue lost to negative reviews?
Keep the program cost on its own line, separate from the estimated damage. Mixing them makes it impossible to judge whether the response was worth paying for. Compare the program fee with a range of possible revenue and contribution differences, including a case where reviews have no effect at all. That zero case is honest when you cannot yet show what the reviews changed.
How can a business protect revenue and keep costs down when its reviews turn negative?
Fix any verified service failure straight away rather than waiting for perfect proof of lost sales. Then check whether something else explains weaker results, such as a price increase, less advertising, a seasonal lull or an unanswered phone. Spending on a large program when the real issue is a broken form wastes money. Clear up inconsistent information across listings and give important complaints a named owner.