
How wills, corporate, tax and IP lawyers get more clients

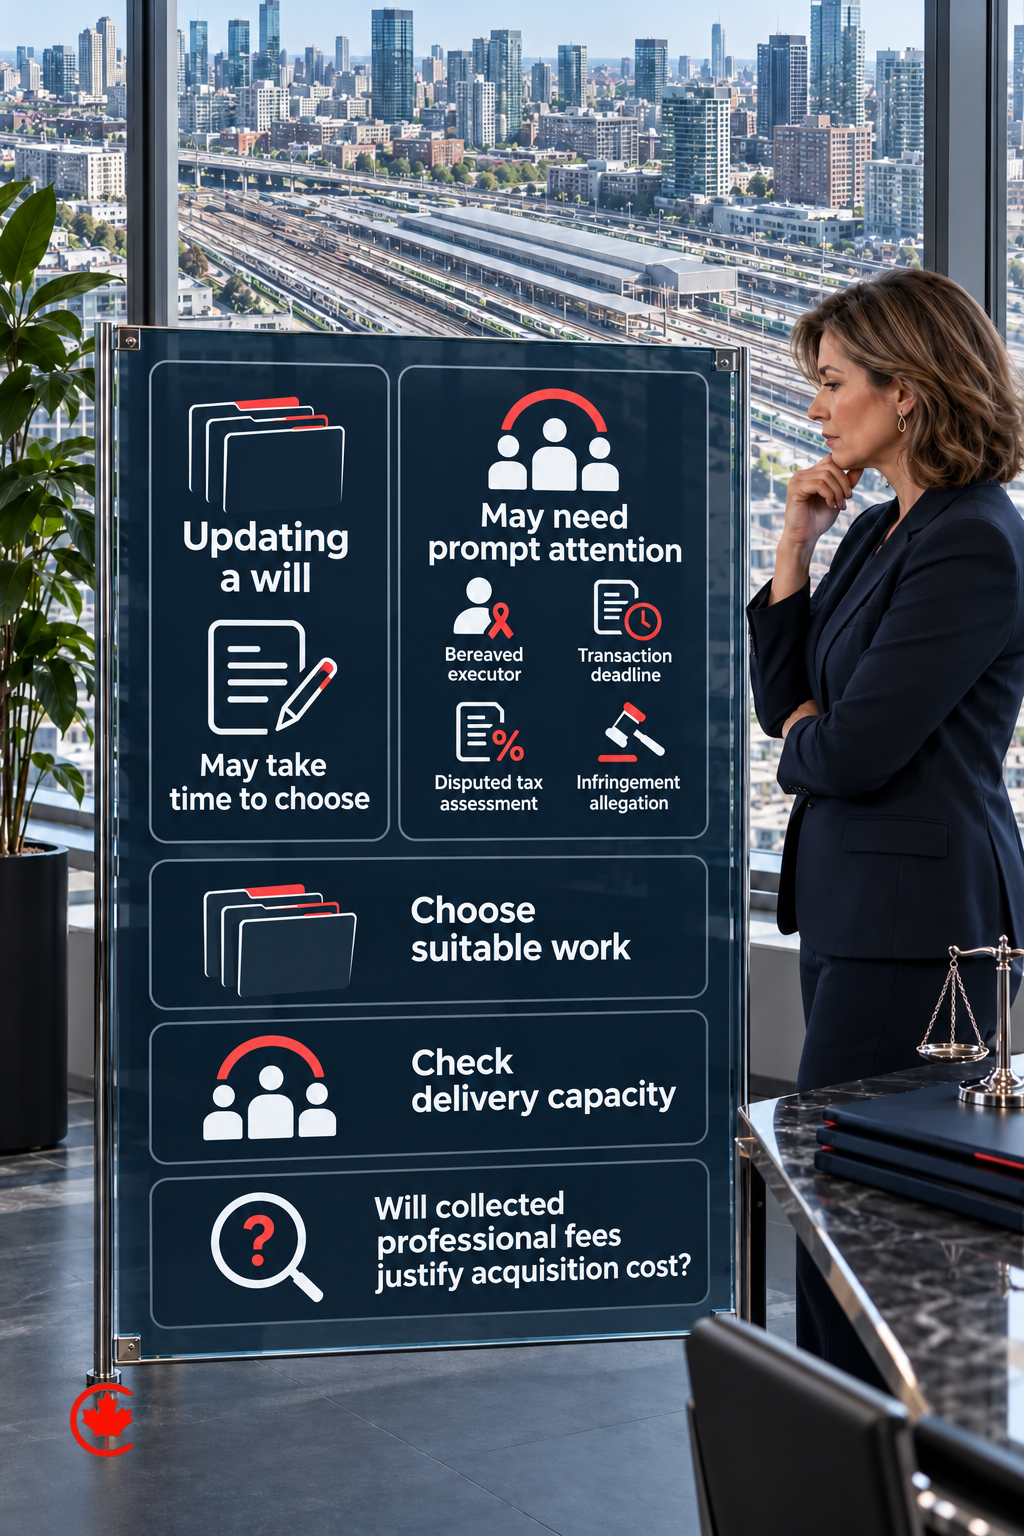
Wills, corporate, tax and intellectual-property practices do not share one client journey. A person updating a will may take time to choose. A bereaved executor, a business facing a transaction deadline, a taxpayer with a disputed assessment or a company receiving an infringement allegation may need prompt attention. Marketing that describes all these clients as calm, long-term planners misses important needs and can send the wrong expectations into the firm.
For the practice owner, the objective is not simply more enquiries. It is more appropriate work, a manageable delivery commitment and collected professional fees that justify the acquisition cost. This guide helps owners compare offers, channels and marketing suppliers across four distinct practice areas. Its scenarios and financial examples are hypothetical, not client results, fee benchmarks or legal advice. The firm’s qualified professionals remain responsible for determining legal scope and approving regulated content.
Search demand by practice area
Search estimates can establish that people look for a service; they cannot tell a firm how many suitable clients it will win. The figures below are Canada-wide estimates of average monthly searches, with each search ranked by its relative cost per click (CPC). These are end-client service queries, not the cost of a law-firm owner looking for a marketing agency.
| Client search | Average monthly searches across Canada | Relative cost per click |
|---|---|---|
| intellectual property lawyer | 590 | Highest in this list |
| tax lawyer | 1,600 | Middle |
| estate lawyer | 2,900 | Middle |
| will lawyer | 2,400 | Lowest in this list |
We plan and run estate lawyer SEO for law firms in Toronto and across Canada, scoped in writing after a free review.
The comparison does not show that wills work is profitable to advertise or that IP practices depend more on referrals. CPC is neither client value nor cost per accepted file. A smaller search figure can accompany a valuable specialist service, but it can also mean that a broad advertising plan has limited relevant demand. Do not add closely related searches together as though each represents a different person, or treat a national estimate as the market available to one office.
Use the data to ask better purchasing questions. Which services is the firm trying to grow, in which jurisdictions, and with what evidence of actual fit? A proposal for corporate work needs its own relevant basis rather than borrowing the estate or tax figures. The same applies to tax planning versus disputes and trademark work versus patent matters. A generic label can conceal important differences in the enquiry, scope and decision period.
Wills and estates: three distinct journeys
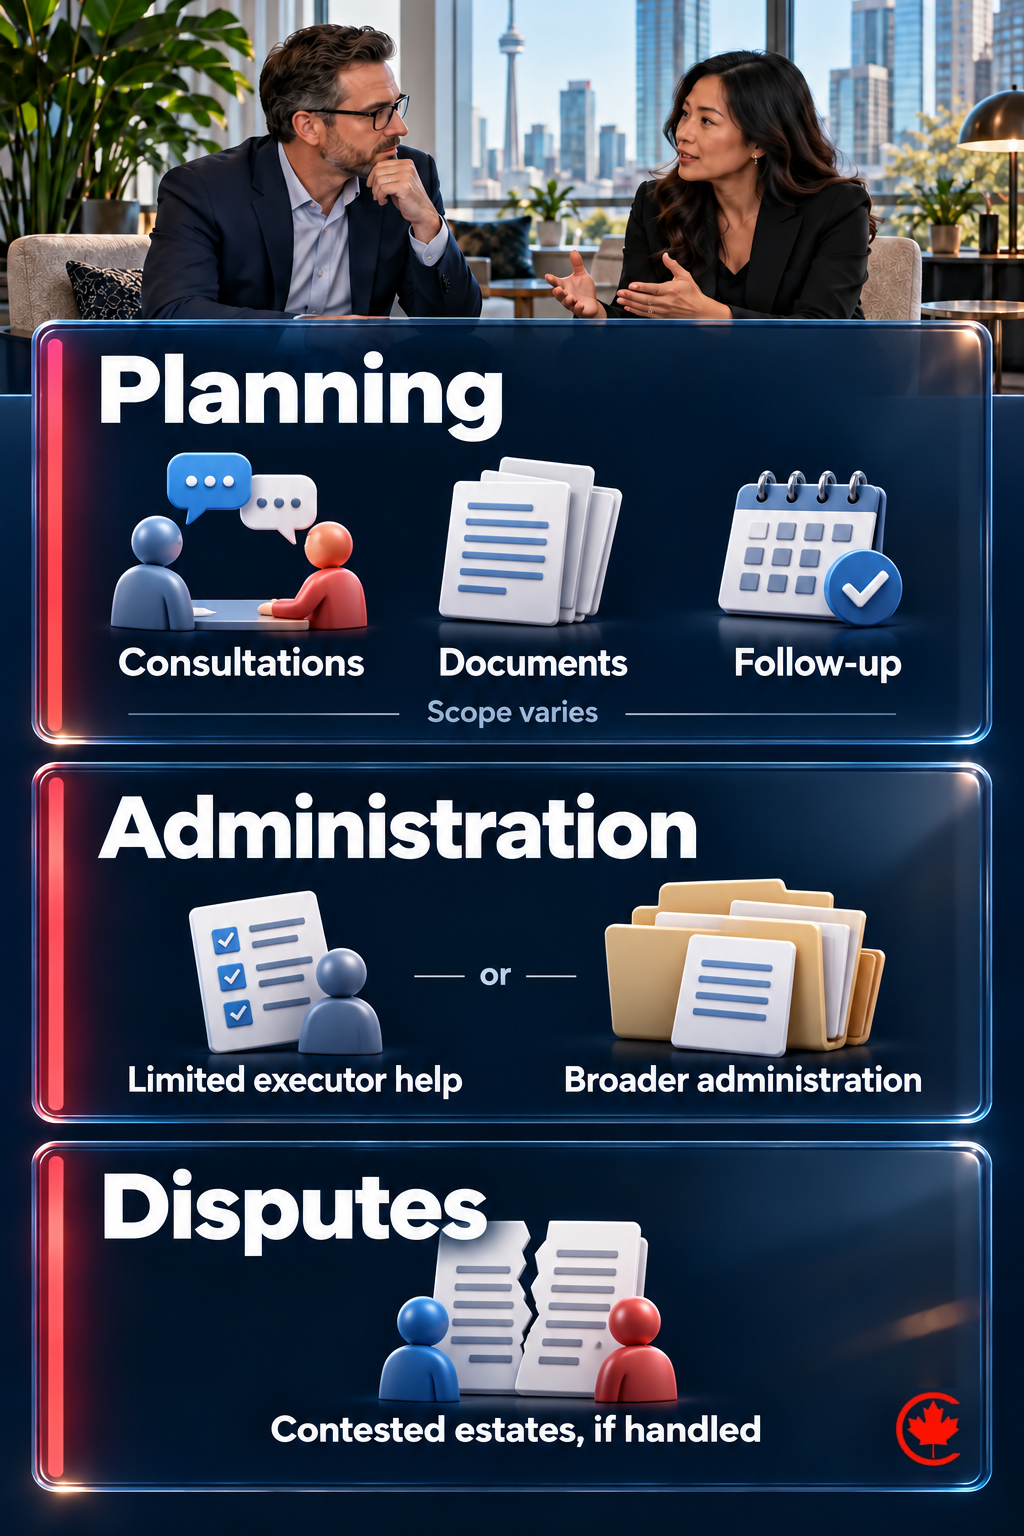
Planning clients, estate-administration clients and people facing a dispute need different explanations. A planning prospect may be trying to understand what an engagement includes and whether the firm is approachable. An executor may need help making sense of a new responsibility. Someone in a conflict may need to know whether the firm acts in contested matters at all. A single promise to “protect your family’s future” does not answer those different hiring questions.
For planning work, make the service boundaries understandable without steering the visitor toward a particular legal instrument. Explain the kinds of matters considered, the initial conversation, how a quote is established and the arrangements actually offered for meetings. The value proposition can include clear communication and a defined engagement experience when those descriptions are true. It should not promise that a document will prevent every dispute, minimize every tax liability or suit every family situation.
A package can make a planning decision easier if its assumptions are visible. A single-person offer and a couples offer may involve different scope, but a two-person label alone does not tell the buyer what is included. The firm should explain which consultations, documents or follow-up steps form part of its actual offer and what requires individual assessment. Any advertised fee and qualification needs the appropriate professional approval before publication. Do not claim that fixed fees inherently convert better.
Consider a hypothetical comparison. One prospective client wants a straightforward review of existing planning documents. Another owns a business, has connections in more than one jurisdiction and wants advice involving several family members. The same online package may not be appropriate for both. Useful marketing helps the second person recognize the need for a scope conversation without implying that the first person’s matter is automatically simple or that a questionnaire can make the legal assessment.
Dispute work deserves a clearly identified route. If the practice does not handle contested estates, its marketing should not attract those enquiries by implying otherwise. If it does, the page should accurately describe the types of matters considered and the first contact process, without sensationalizing family conflict or predicting the result. An enquiry form should not suggest that a deadline is protected or that representation has begun merely because someone has described a dispute.
A planning-oriented marketing proposal may appropriately emphasize a considered introduction and understandable package scope. An administration or disputes proposal may instead need to prioritize fit, responsible handling of uncertainty and accurate availability. The owner should compare those proposed outcomes rather than buying the same content and reporting package for all three. A full planning calendar is not evidence that the firm is attracting the executor or contested work it actually wants.
Corporate and commercial practices
Corporate clients arrive with business decisions, not just a general desire to hire a lawyer. A founder may be considering formation, an established company may need contract support, and an owner may be preparing to buy or sell a business. These situations differ in complexity, budget authority and urgency. A useful website tells each reader whether the practice considers that kind of engagement and what information is needed to begin assessing fit.
A formation offer should clarify its actual scope rather than imply that a filing is a complete solution for every business. The visitor needs to distinguish a narrowly defined service from broader advice and continuing work. A company with several owners may need a different conversation from a sole founder; the firm, not the marketing page, determines the appropriate advice. The promise should describe the engagement the firm offers, not guaranteed tax savings, financing or protection from future disagreements.
For established businesses, relevant evidence often concerns the work and context the practice genuinely understands. A page might identify the kinds of contracts or transactions considered and the professionals responsible. It should not rely on a list of industries so broad that it conveys no useful fit. Claims of expertise need substantiation, and examples must avoid disclosing confidential counterparties, terms or circumstances. An illustrative scenario should be identified as such rather than dressed as a completed deal.
A business-sale enquiry is not equivalent to a routine formation request. The owner may be working with an accountant, broker or other adviser and may have an anticipated timetable that the firm has not assessed. The website should make it easy to request an appropriate discussion without promising a closing date or an all-inclusive fee before scope is known. A marketing supplier should recognize that more conversations may be needed before an engagement decision can be fairly evaluated.
Consider a hypothetical manufacturer seeking contract support while preparing for a possible acquisition. A proposal focused only on inexpensive incorporation enquiries would miss that audience. A more relevant explanation would help the owner understand the kinds of business work the firm considers, who might be involved and how an initial scope discussion works. That does not require publishing a negotiation playbook or implying the practice can serve every industry and transaction size.
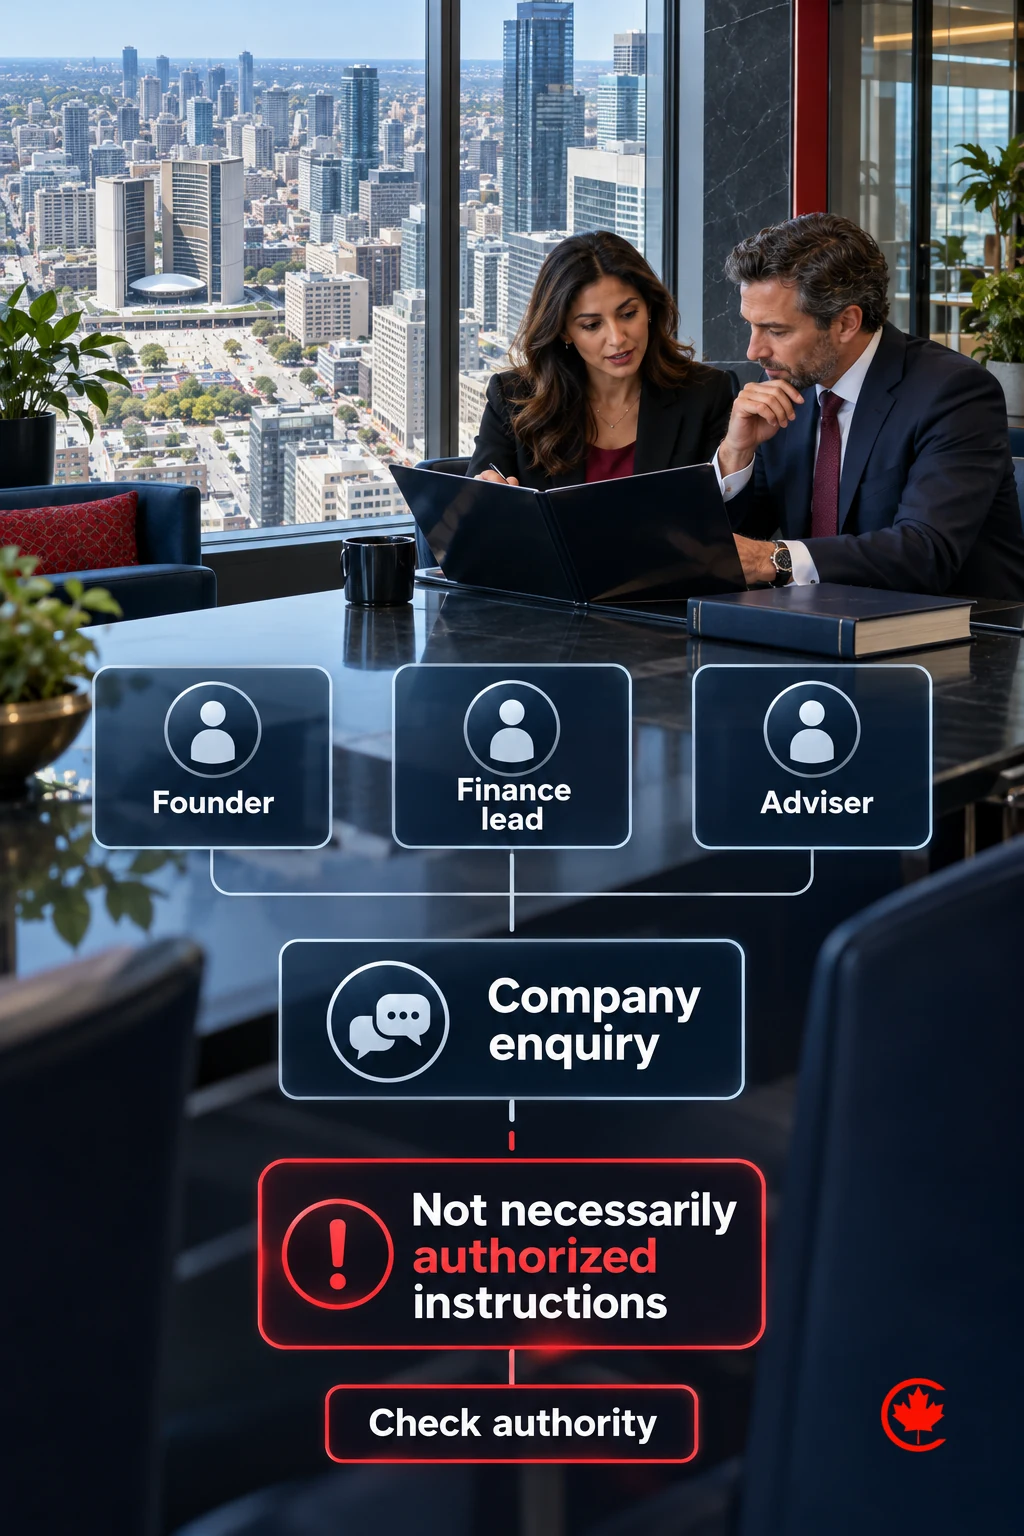
The person making first contact may not be the only decision-maker. A founder, finance lead and outside adviser can each ask different questions about the same prospective engagement. Marketing should make the firm’s scope understandable to them without requesting a confidential deal summary merely to qualify interest. A proposal can distinguish a suitable opportunity from an authorized instruction: an interested employee’s enquiry is not necessarily approval from the business to retain counsel. That distinction helps the owner interpret activity without overstating the number of clients won.
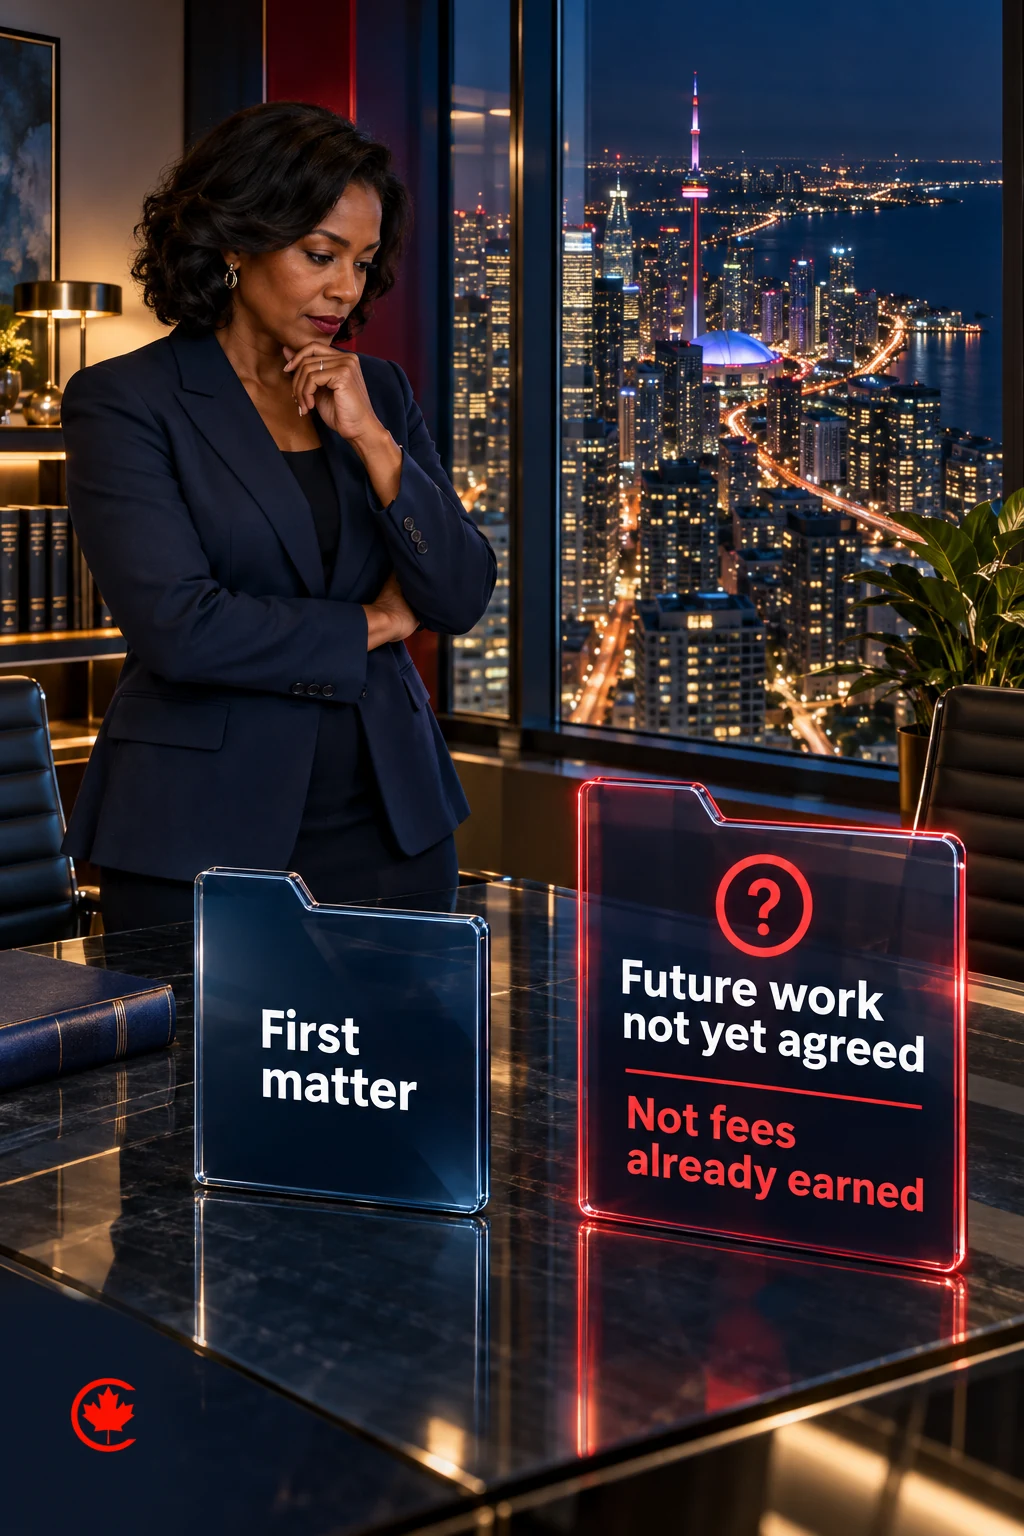
Ongoing corporate work also needs honest measurement. An initial matter may lead to a continuing relationship, but the marketing report should distinguish work already agreed from hoped-for future instructions. A client who has incorporated through the firm has not automatically purchased annual support, shareholder advice or a future sale engagement. Owners can value relationship potential without counting several years of speculative fees as an immediate return on acquisition spending.
When comparing suppliers, ask how the proposal distinguishes start-up, established-business and transaction opportunities. The answer should influence the scope of the material purchased and the meaning of a successful enquiry. A supplier that reports every corporate contact as an equivalent lead may be overlooking the firm’s commercial priorities. The right comparison is between suitable opportunities and the firm’s actual delivery capacity, not simply between the number of form submissions generated by each topic.
Tax law practices
Tax marketing needs to separate planned advice from a problem that already has a timetable. A business considering a transaction may be looking for coordinated planning support. A person with a notice, audit concern or dispute may be anxious and unsure who can help. Both may use a broad tax-lawyer search, but a page that assumes one journey can mislead the other. The firm should state what work it actually accepts rather than use the breadth of “tax” to imply universal coverage.
A planning page can explain the kinds of clients and matters considered, the role of the initial scope discussion and how the firm works with other advisers when appropriate. It should not promise a particular tax reduction or present a general article as a tailored strategy. A business owner comparing providers needs to understand relevant experience, responsibilities and the basis for fees. They do not need a marketing page to recommend a structure without reviewing their circumstances.
Dispute-related enquiries call for a different tone. Calm, specific language is more useful than fear or an assurance that the firm can make a liability disappear. A visitor should be able to recognize whether their general issue falls within the practice and how to request a review. Avoid publishing a universal response deadline: the lawyer must assess the actual document, issue and circumstances. An automated acknowledgement cannot establish that a deadline has been reviewed or representation accepted.
The first-contact experience should not require a tax return, account number, complete notice or detailed financial history in a general marketing form. The firm can ask for a broad description of the matter, the relevant jurisdiction, whether timing is a concern and a suitable contact route. Further records belong in an approved intake process after the firm determines what is appropriate. This separation improves the purchasing discussion without turning the agency into a recipient of the client’s tax file.
For example, a hypothetical small-business owner may approach the firm after an accountant identifies a disputed assessment. Another may seek planning advice ahead of a sale next year. The first enquiry needs an accurate route for assessing the present issue and timing. The second needs a clear scope conversation and coordination expectations. Sending both toward a generic “save taxes now” offer would conceal the very differences that should shape the firm’s service and marketing investment.
The relationship with accountants should be explained carefully. A potential client may want to know whether the legal team can work alongside an existing adviser, but that does not authorize sharing documents or imply that every accountant and lawyer has the same role. The firm should define responsibilities for the particular engagement. Marketing should avoid disparaging accountants to create urgency or presenting a referral as proof that the firm has already accepted the matter.
A further distinction is whether the practice offers the work the visitor expects from the word “tax.” Routine return preparation, broader accounting support and legal advice about a dispute are not interchangeable descriptions of a firm’s services. The owner should review whether the website creates confusion about that boundary. If many enquiries seek a service the practice does not offer, more visibility is unlikely to fix the mismatch. The useful purchasing decision may be a clearer explanation of fit before additional advertising is considered.
For the owner evaluating results, distinguish consultations from accepted engagements, and agreed fees from collected earnings. A larger disputed amount is not the firm’s revenue and does not establish the likely value of the file. A tax programme may produce fewer but more involved opportunities, making a short observation period inconclusive. The proposal should make that uncertainty visible rather than rely on one hypothetical high-value client to justify any level of spending.
Intellectual property practices
IP marketing should not treat every prospect as a start-up seeking a trademark registration. A business may need help with a brand, an invention, licensing, copyright-related work or a developing dispute. An established organization may be assessing a wider portfolio or a transaction involving IP assets. The website should make the actual practice scope understandable without suggesting that one service protects every kind of intangible asset.
A trademark-focused offer needs a clear distinction between the professional work included and an outcome controlled by a public authority or another party. A prospective buyer should understand whether the engagement concerns an initial assessment, an application or a broader matter, and what requires a separate scope. Do not promise registration, a fixed decision date or worldwide protection as an automatic result of purchasing a package. Any legal explanation should receive appropriate professional review.
Patent-related prospects may have different selection questions. They may want to understand the professionals’ relevant qualifications and whether the practice considers work in their technical field. A page should describe verified credentials accurately and avoid treating every lawyer as an authorized patent agent. The firm should also decide how an inventor can make an initial enquiry without putting an unpublished invention into a general marketing form. Detailed technical disclosure is not a reasonable prerequisite for learning whether a conversation is possible.
Licensing and commercialization work involves yet another buying journey. A business may need to understand the scope of legal support around an agreement rather than the process for obtaining a registration. A useful page can identify the types of matters the firm considers and explain how scope and coordination are established. It should not offer a universal royalty rate, standard negotiation answer or assurance that a deal will close simply because the practice is involved.
A company facing an allegation needs a visibly different route from one planning a brand launch. Its questions may concern whether the firm handles disputes, whether it can assess the stated timing and what information should be shared first. Marketing should not encourage the visitor to publish allegations, send confidential evidence through an advertising form or assume that a standard package resolves the matter. The firm’s first response should explain how it will assess whether it can act, not guarantee the legal outcome.
Consider two hypothetical enquiries. A founder asks about a proposed product name before launch, while an established manufacturer wants advice about licensing technology in several markets. Both may be described broadly as IP work, but the appropriate scope, professional involvement and evaluation period differ. A marketing proposal that only promotes low-friction registrations may attract the first category while doing little for the second. The owner should decide which work the practice wants before judging the value of enquiry volume.
For an in-house legal or business team, the next buying step may be a carefully scoped professional introduction rather than a consumer-style free-call offer. A sole inventor may need a simpler explanation of whom they would speak with and what an initial consultation covers. Neither path is automatically superior. Ask whether the marketing proposal respects the audience’s decision process and available evidence, including when a paid consultation is accurately described rather than implied to be free.
IP firms should also separate client assets from their own revenue when evaluating acquisition. The claimed value of an invention, brand or transaction does not equal collectable professional fees. A substantial opportunity can require lengthy assessment or produce no engagement. Reporting should identify the work actually accepted and its delivery cost while leaving uncommitted portfolio potential as uncertain. That creates a more defensible investment discussion than comparing a historical click price with a speculative asset valuation.
Local search and your Google Business Profile
Local information should reflect the firm as it actually operates. Google’s guidance distinguishes business locations and individual practitioners and does not treat a mailing address as an automatically eligible office. A national or remote-service claim does not remove the need for accurate representation. Ask a supplier how the proposed presence matches real locations, contact arrangements and the work the firm can accept. See Google’s business representation guidelines.
The local buying experience differs by practice. A planning client may care about practical meeting arrangements; a corporate decision-maker may mainly want to verify the right professional and service scope. Neither needs an invented branch office or an unsupported proximity claim. Assess whether the information helps a genuine prospect contact the correct team. Profile views and website visits can support that journey without proving that each interaction created a new client.
Referral networks and professional introductions
Referrals can complement direct enquiries, but no single channel should be declared the biggest without the firm’s own evidence. Planning practices may receive introductions from advisers; corporate and tax matters may involve existing professional relationships; IP work may involve founders, business counsel or sector contacts. The introduction is only the beginning. Fit, client choice, confidentiality and the actual engagement process still matter.
Compare referral quality by the work the firm wants, not only the number of introductions. A small source of suitable business-sale enquiries may serve a different objective from a larger flow of routine planning contacts. Do not offer referral payments, gifts or fee-sharing arrangements merely because they appear in a marketing proposal. The responsible professional must review the applicable rules and proposed arrangement, particularly where non-lawyers are involved. This guide gives no nationwide permission for compensation.
Paid search matched to the practice
A paid-search proposal should explain which buying journey it is intended to support. Planning consultations, executor enquiries, corporate transactions, tax disputes and IP registrations should not be evaluated as interchangeable leads. The owner needs to understand the target work, total investment, capacity requirements and observation period. A fast increase in calls may be unhelpful if the firm cannot accept the matters or if the enquiries concern a service outside its scope.
The budget discussion must include more than media spending. Management, approved project work, reporting and additional intake effort may materially change acquisition economics. Historical CPC can inform a discussion but cannot prove profitability. A firm that earns a predictable fee on a defined engagement faces a different decision from one assessing complex opportunities over several months. Neither should be offered a guaranteed number of accepted files based only on a keyword estimate.
Some legal subjects also raise advertising-policy constraints. Google’s sensitive-interest policies identify bereavement among personal-hardship examples and restrict advertiser-curated audiences for sensitive services. A supplier should assess the actual service and proposed use rather than assume that all visitor follow-up is available. This is not a blanket ban on Search advertising. See Google’s relationship-hardship policy.
For scope discussions, see Google Ads for lawyers and the guide to cost per click by practice area. Neither supplies a guaranteed acquisition price for a particular firm.
Content that supports an informed hiring decision
Useful content should answer the prospective client’s selection question without becoming unreviewed legal advice. A planning prospect may need to understand the initial engagement; a business owner may want to know whether the firm handles a particular kind of transaction. A tax or IP dispute prospect may need a clear statement of scope and contact expectations. Choose material that helps the intended reader recognize fit rather than publishing the same generic explanation under four practice labels.
Evidence of competence should be relevant and verifiable. Professional biographies, accurately described experience and approved examples can help explain the practice. Do not invent results, imply that a hypothetical scenario is a past client or copy a competitor’s claims. A marketing supplier should identify who will review technical legal statements and what maintenance is included when the underlying information changes. A large article quota is not a substitute for that responsibility.
Client retention and cross-practice growth
A completed matter can create a relationship, but it does not automatically authorize every future promotional use of the client’s details. Government CASL guidance distinguishes express and implied consent and describes requirements for commercial messages. The firm should establish the applicable basis and handle identification and unsubscribes appropriately. Necessary engagement communications and general marketing should not be treated as identical. See Canada’s commercial-email consent guidance.
Cross-practice introductions should serve a genuine client need. A corporate client may later require IP advice, but a newsletter should not presume confidential circumstances or imply that additional work is mandatory. Evaluate continuing relationships through actual new instructions and earned collections, not a projected lifetime value assigned to every contact. Software may help keep permitted communications organized; choosing a CRM for small business in Canada provides general context, not a substitute for the firm’s confidentiality and professional requirements.
Rules, approvals and supplier responsibilities
The firm should approve the meaning of its advertising under the rules applicable to its professionals and jurisdictions. That includes titles, claimed expertise, fees, testimonials, images and statements about results. A generic disclaimer cannot repair an unsupported headline. Where current authoritative support is missing, narrow or hold the claim rather than treating an agency’s familiarity with legal marketing as regulatory approval. This guide does not provide a national compliance opinion.
Responsibility should be clear in the supplier agreement. Identify the professional who approves the material before it goes live and the scope for later corrections. The guide to lawyer advertising rules in Canada offers background, not legal sign-off for a particular campaign or practice.
Measuring the programme by practice
Define a useful enquiry separately for each service. A planning contact, an executor seeking help and a business evaluating a transaction may all be appropriate, but their next steps differ. Reporting should distinguish unsuitable contacts, appropriate consultations, accepted engagements, work completed and earned fees collected. A single blended conversion rate can hide both successful specialist work and a costly mismatch in another practice area.
Use an observation period suited to the engagement. A corporate opportunity still under discussion is not necessarily a failed lead, but it is not revenue either. An accepted tax matter may have significant work and billing ahead. A completed planning engagement may be easier to evaluate sooner. Keep those categories visible instead of using future estimated fees to make the present period look stronger.
Attribution should preserve uncertainty. A person may learn about the firm from an accountant, read several pages and later respond to an advertisement. The last interaction is not the whole relationship. Ask a supplier to explain what the evidence can identify and what remains unknown, without sending confidential legal narratives into marketing reports. The owner’s decision should rest on suitable work and contribution, not the claim that every accepted client can be assigned perfectly to one channel.
Estate administration: supporting executors well
An executor’s enquiry may combine uncertainty, responsibility and bereavement. A useful service explanation should tell the person whether the firm considers the matter, how the first discussion works and how the engagement’s scope is established. It should not assume that the visitor already knows the correct legal terminology or has every document ready. At the same time, the website should avoid making individualized statements about what a particular estate must do.
The owner should distinguish limited assistance from a broader administration engagement when presenting the firm’s actual services. A prospective client comparing firms needs to understand what is being offered and what remains outside that scope. An apparently low fee can be misleading if the surrounding copy implies work not included. A responsible marketing proposal makes those distinctions visible and leaves the lawyer to determine the appropriate engagement.
For a hypothetical executor living away from the deceased person’s community, practical communication arrangements may matter as much as office proximity. The firm can accurately explain available meeting options and how information is requested without promising remote completion of every legal step. That is a different proposition from a planning package and a different evaluation from estate litigation. Keep these differences in the report so administration enquiries are not counted merely as another form of will preparation.
Packages and pricing for solicitor work
A package is a defined offer, not proof that the underlying matter is simple. Planning documents, formation work or a particular IP service may be presented with a stated scope when the firm can do so accurately. Complex corporate transactions and tax disputes may require a different quoting process. The marketing task is to make the distinction understandable, not force every service into a fixed-price box for visual consistency.
Compare hypothetical offers on the same basis. A consultation-only proposal and a proposal including defined follow-on work are not equivalent because their headlines are similar. Identify professional work, third-party charges, applicable taxes, exclusions and the circumstances in which scope is reassessed. The article supplies no recommended legal-service price. A clearer explanation can support an informed choice while still acknowledging that the lawyer must review the actual matter.
Marketing supplier pricing needs the same discipline. Media spend is separate from management fees. Do not assume cancellation-at-will or unconditional ownership.
Website essentials for solicitor practices
The first contact should collect enough information to route an enquiry without demanding the whole legal story. Family and asset details, tax records, confidential agreements and unpublished inventions do not belong in a generic form merely to help marketing classify a lead. The firm can request a broad service category, relevant location, timing concern and appropriate contact information, then determine the necessary next steps through its approved intake process.
The website should also distinguish an initial enquiry from an established professional relationship. An appointment request, automated reply or uploaded file should not imply that a lawyer has reviewed a deadline or accepted instructions. Any statement about urgent response needs to match actual availability. A planning-focused practice should not advertise round-the-clock dispute assistance simply because its website form is always accessible.
When comparing a redesign with targeted improvements, ask what prevents an appropriate prospect from making an informed contact today. The answer might be unclear scope, inaccessible language, outdated professional information or confusing navigation. A replacement website may or may not be necessary. The proposal should explain how it protects useful existing content and contact routes, what the firm must approve and what evidence will show that the agreed work has been delivered.
Working with accountants: a clear professional relationship
Accountants may be involved in planning, transactions or disputes, but those are not interchangeable referral situations. A business-sale introduction can involve a broader team and an evolving timetable. A disputed-tax matter may require prompt assessment of a specific issue. The legal practice should make its accepted work and contact route clear enough that an adviser can suggest an appropriate next conversation without promising the firm will act.
The client controls the engagement decision and relevant information-sharing permissions. A business relationship between professionals should not be treated as blanket authority to exchange documents, contact details or sensitive circumstances. Marketing can describe a willingness to work collaboratively where appropriate, but the actual responsibilities belong in the engagement. Do not imply that every adviser introduction carries preferred access, a guaranteed outcome or permission for referral compensation.
For the practice owner, concentration is a commercial consideration. Losing one important source may materially change enquiry flow even when other channels look stable. Compare the type and suitability of referred work with direct enquiries before choosing a diversification investment. The objective is not to replace trusted relationships indiscriminately; it is to understand dependencies and decide where an additional source of suitable work would genuinely improve the practice.
Two hypothetical investment examples
Suppose a planning practice spends CAD $4,500 on a defined acquisition group: CAD $2,000 media, CAD $1,200 management, CAD $800 allocated website and reporting work, and CAD $500 additional intake effort. Assume it receives 40 enquiries, considers 25 suitable, accepts 15 engagements and completes and collects on 12. At an assumed CAD $900 earned fee and CAD $350 direct delivery cost per completed engagement, contribution before acquisition is CAD $6,600 and after acquisition is CAD $2,100. These invented amounts are not supplier or legal-service prices.
The same calculation looks different for a hypothetical corporate programme. Assume CAD $6,000 all-in acquisition spending, made up of CAD $2,500 media, CAD $1,500 management, CAD $1,200 allocated content and reporting work, and CAD $800 additional intake. It produces 12 enquiries, six suitable opportunities and two accepted engagements. Each eventually collects CAD $7,000 in earned fees and costs CAD $3,500 to deliver, leaving CAD $1,000 contribution after acquisition. Fewer engagements do not automatically make it worse, but the result depends on completing and collecting both.
For a separate cash illustration, assume only one of those corporate engagements has paid its CAD $7,000 fee, while the full CAD $7,000 delivery cost and CAD $6,000 acquisition cost have actually been paid by the review date. The cash shortfall is CAD $6,000 at that date; costs incurred but not yet paid would instead be amounts still owing. An eventual positive contribution does not eliminate the funding gap or collection risk. The earlier planning-practice example also changes if its three unfinished engagements have already consumed staff time; those costs must be included rather than hidden because the matters have not completed.
Both examples exclude fixed overhead and other costs not stated, use amounts net of recoverable sales taxes and exclude client funds, taxes and pass-through disbursements from earned revenue. Non-recoverable costs must be added. They illustrate questions an owner should ask, not an expected return. For tax and IP work, build the same distinction between committed scope, actual delivery cost and collected earnings without assuming that a large disputed amount or valuable asset creates an equally large professional fee.
A 90-day decision plan
During the first month, choose the services the firm actually wants to grow and identify their different capacity constraints. Planning appointments, administration matters, commercial transactions, tax disputes and IP work should not inherit the same success definition. Review the proposed scope, spending and approval responsibilities before commissioning a broad programme. Where evidence is weak, agree on what needs to be learned rather than accepting a precise forecast unsupported by the practice’s circumstances.
In the second month, assess whether the agreed material makes each buying journey clearer. A founder, executor, taxpayer and IP prospect should be able to recognize an appropriate service and understand the first step without overdisclosing sensitive information. Check the accuracy of package boundaries, professional descriptions and response expectations. The owner should be able to explain the value of the work purchased without relying on page counts or generic visibility claims.
By the third month, review suitable enquiries, accepted work, delivery capacity and collections, with unfinished opportunities identified separately. Decide whether to continue, narrow or adjust the programme for a stated business reason. A longer transaction may require more time before its financial outcome is known. Sustainable growth means a credible relationship between the work the firm seeks, the promises it makes and the fees it can earn and collect, not a single channel prescription applied to four different practices.
For an initial scope discussion, see estate lawyer SEO and our broader law firm marketing services. The law firm marketing playbook provides related buying context.
Frequently asked questions
How do wills and estates lawyers get clients?
Planning, estate administration and contested matters need different offers and contact routes. Appropriate local visibility, useful service explanations and professional introductions can support enquiries. Evaluate suitable engagements and earned collections rather than assuming one channel or package works for every estate practice.
Should we advertise fixed fees for wills?
A defined package can help a buyer compare scope if its assumptions are accurate. Explain inclusions, exclusions, applicable taxes and when individual assessment is required. The responsible professional should approve the complete advertised offer under the applicable rules; a fixed fee does not guarantee conversion.
How do corporate lawyers get clients online?
Help founders, established businesses and transaction clients recognize whether the practice handles their needs. Explain relevant scope, verified experience and the first discussion. Measure appropriate opportunities separately from routine enquiries and do not count uncommitted future work as revenue.
Where do tax lawyers find clients?
Direct search and professional introductions may both matter, but planning and dispute enquiries need different explanations. Clarify accepted work, confidentiality and contact expectations. The firm's own evidence should guide investment; a historical click price does not establish profitability or likely professional fees.
How do IP lawyers attract start-ups?
Explain the specific work the firm considers, relevant credentials and the initial engagement. Distinguish trademark, patent, licensing and dispute needs. Do not guarantee registration or ask inventors to disclose unpublished technical details through a general marketing form.
Can lawyers pay accountants for referrals?
A professional introduction does not by itself authorize compensation or information sharing. The responsible professional must review any payment, gift or fee-sharing proposal under the applicable rules, particularly where non-lawyers are involved. This guide provides no nationwide permission.
Do Google Ads work for wills and estates?
They may support suitable enquiries, but results depend on scope, capacity and all-in cost. Planning, administration and disputes need separate evaluation. The supplier must also assess applicable advertising policies, including sensitive-interest restrictions; neither a click estimate nor a campaign guarantees accepted work.
What content works for solicitor practices?
Content should help the intended client judge service fit, scope, relevant experience and the next step. A founder, executor, taxpayer and IP prospect need different explanations. Legal statements require current support and appropriate professional approval, not copied competitor claims.
How do we keep solicitor clients coming back?
Offer relevant further services only when appropriate to the relationship and the client's needs. Distinguish engagement communications from promotion, establish the applicable consent basis and manage unsubscribes. Count actual new instructions rather than assumed lifetime value.
How do we measure solicitor marketing?
Separate enquiries, suitable opportunities, consultations, accepted engagements, completed work and earned collections by practice. Include all relevant acquisition and delivery costs and show unfinished matters. A larger asset value, disputed amount or proposed transaction is not the firm's revenue.