
Toronto · Life insurance leads
Life insurance leads in Toronto
Your own quote requests and referrals, contacted fast, nurtured with consent and tracked through to placed policies.
Enquiries for term, permanent, critical illness, disability, final expense and group benefits for licensed advisors and brokerages in Toronto and the GTA and across Canada, from campaigns you own.
- BBB A+ accredited
- 18 years in business
- Mon to Fri 9 to 6, Sat 10 to 2
Get a custom proposal for your life insurance lead
Tell us which products you advise on and where you are licensed. We reply within one business day.
Please do not share passwords or other sensitive details here. We never sell your contact information and we comply with Canadian privacy law
(privacy policy).
What advisors get
Enquiries that are yours
Leads from your own pages, campaigns and partners, not shared lists.
Faster first contact
Instant alerts, booking links and after-hours answering for every quote request.
Consent on record
Form wording, timestamp and source stored for every contact.
Reporting to placed policies
Enquiries tracked by source and product through to placement.
What life insurance lead generation includes
Each piece is chosen after a free review and quoted in writing.
- Product landing pagesTerm, permanent, critical illness, disability, final expense and group benefits.
- Light quote request formsContact, province, product and consent, with no health questions.
- Needs calculatorA coverage estimate tool that leads to a booked conversation.
- Search and social campaignsProduct campaigns limited to the provinces where you are licensed.
- CS+ alerts and bookingInstant advisor alerts and a booking link for the consumer.
- Consent-based nurtureEducation emails for people who are not ready yet.
- Centre-of-influence programReferral pages and tracking for mortgage brokers, accountants and planners.
- Placed policy reportingSource to placement reporting kept in your CRM.
How pricing works for life insurance leads
Lead generation is quoted in writing. Ad spend is paid to the platforms and shown separately from our fees.
Product pages and forms
Quoted in writing
Advisors who need pages and quote forms they own
- Product landing pages
- Quote request forms
- Needs calculator
- Consent records
Lead campaigns
Quoted in writing
Advisors ready to run search and social campaigns
- Search campaigns by product
- Social lead forms
- Compliance review step
- Monthly optimization
Contact and nurture
Quoted in writing
Advisors losing leads after the first call
- CS+ instant alerts
- Booking links
- After-hours AI answering
- Email nurture series
Referral and group growth
Quoted in writing
Advisors building partners and employer clients
- Centre-of-influence pages
- Partner tracking
- Group benefits page
- LinkedIn content plan
Ad spend and software licences are paid to the platform directly and shown separately from our fees.
Life insurance leads
How advisors build a lead flow they own
Life insurance leads, for a licensed advisor, are people who have asked about coverage: a quote request for term life, a question about critical illness or disability cover, a family protecting a new mortgage, an older client asking about final expense, or an employer looking at group benefits. This page is for life insurance advisors, agencies and brokerages that want those enquiries to come from their own campaigns, pages and referral partners instead of shared lead lists, and to turn them into placed policies. Canada Create is a Toronto digital agency at 126 Willowdale Avenue, Suite 3, serving advisors and brokerages across Canada since 2008.
- How Canadians shop for life insurance online
- Bought shared leads compared with your own enquiries
- Product pages, quote requests and needs calculators
- Search and social lead campaigns within platform rules
- Speed to contact and booking
- Nurture for people who are not ready yet
- Referral and centre-of-influence programs
- Group benefits enquiries from employers
- Measuring placed policies, not just leads
- Licensing, fair treatment and consent rules for life insurance leads
- How we work with advisors and brokerages
- What life insurance lead generation costs
- Choosing a life insurance lead partner
- Book a life insurance lead review and get a custom proposal
How Canadians shop for life insurance online
Life events start the search
Very few people wake up wanting a life insurance policy. They search after something changes: a baby on the way, a first home and a new mortgage, a marriage, a business partner, a diagnosis in the family, a friend’s sudden loss, or a group plan that ends with a job. The searches reflect that: “life insurance quote”, “term life insurance Canada”, “how much life insurance do I need”, “critical illness insurance”, “mortgage life insurance vs term”, “life insurance for seniors” and “life insurance broker near me”.
What they want before they talk to anyone
Most consumers want a sense of what coverage might cost and how the products differ before they speak with an advisor. They worry about medical exams, about being sold more than they need, and about a pushy follow-up. Advisors who give useful education up front, explain the next step plainly and let people choose a time to talk tend to get more conversations from the same traffic than those who lead with “get a free quote” and then call six times.
Where advisor leads differ by product
A young family comparing term policies, a self-employed contractor who needs disability coverage, a couple in their seventies asking about final expense and an HR manager looking at group benefits are four different buyers with different questions, timelines and sales conversations. A lead plan built around one generic “life insurance” form treats them all the same and wastes most of them.
Bought shared leads compared with your own enquiries
How purchased leads usually work
Advisors who search “buying insurance leads” or “life insurance leads for sale” find shared leads, exclusive leads, aged leads and live transfers. Shared leads are often sold to several advisors at once, so the consumer gets a flood of calls and picks whoever sounds least like a telemarketer. Aged leads are older enquiries resold at a lower price. Live transfers connect a call that someone else generated. Each has a place for some advisors, but the advisor rarely knows how the consent was collected or what the consumer was promised on the page they filled in.
Why your own enquiries behave differently
When a person fills in a form on your page, after reading your explanation of term and permanent coverage, they have chosen you. You know exactly what the page said, what they consented to and which product they asked about. That makes the first call easier, keeps your messaging consistent with what your MGA or brokerage has approved, and builds an asset you own: a list of people and a source of enquiries that does not stop when you stop paying a lead seller.
Consent and the do not call list
Any lead you call or text must have valid consent. CASL governs commercial email and texts, and telemarketing calls are subject to the national do not call list rules. With bought lists, you inherit someone else’s consent practices. With your own forms, consent wording, timestamp and source are on record in your CRM.
Product pages, quote requests and needs calculators
One page per product and buyer
Each product deserves a page aimed at the person who buys it: term life for young families and new homeowners, permanent life for estate and legacy planning, critical illness, disability insurance for the self-employed and professionals, mortgage protection compared with personal term coverage, final expense for older Canadians, and group benefits for small employers. Each page explains what the product is, who usually considers it, what affects the cost in general terms (age, amount, term length, health and lifestyle), what the application involves and how to book a conversation.
Quote requests that stay light
A first quote request should ask only what is needed to start a conversation: name, contact details, province, the product of interest, rough coverage amount and the best time to reach them, plus a consent checkbox. Detailed health and lifestyle questions belong in the advisor’s needs analysis and the insurer’s application, not in a marketing form that passes data to ad platforms and analytics.
Calculators and education
“How much life insurance do I need” is one of the most common searches in this trade. A needs calculator that walks through debts, mortgage balance, income replacement, children’s education and final costs, described as an estimate to discuss with an advisor, gives people a reason to engage and a natural reason to book. Short articles on term versus permanent, mortgage life insurance versus personal term, and what happens at a medical exam build trust before the first call. Our financial content writing team writes these in plain language for advisors.
Mortgage protection and personal term
New homeowners are often offered mortgage life insurance by their lender at signing and only later search whether it is the right choice. A page that compares lender mortgage coverage with a personal term policy in neutral terms (who owns the policy, who the beneficiary is, what happens when the mortgage balance falls or the mortgage moves to another lender) answers a question many homeowners have, and positions the advisor as the person to talk to. It must stay factual and avoid disparaging any lender’s product.
Search and social lead campaigns within platform rules
Search campaigns for ready buyers
Search ads on quote-intent words such as “term life insurance quote” or “critical illness insurance Ontario” reach people who are already shopping. Campaigns should send each product to its own landing page, limit geography to the provinces where the advisor is licensed, and exclude research searches that rarely convert. Ad copy must not mislead about coverage or premiums, and “free” should be used only where something is genuinely free with nothing attached, such as the quote conversation itself.
Social lead forms for life events
Social platforms work well for education-led campaigns aimed at life stages rather than health: new parents, homebuyers, business owners. Lead forms on these platforms are quick to fill in but also quick to forget, so the speed of the first call matters even more. Ad platforms apply their own financial services and insurance policies, and some limit the targeting options available for these ads; campaigns must follow them. Our social media advertising service runs these campaigns within those limits.
Compliance review before launch
Most advisors work through an MGA or a brokerage that reviews advertising. Every ad, landing page and email sequence should go through that review before it runs, and the approved version should be kept on file. Building that step into the launch plan avoids pulling a working campaign later.
Messages to avoid
Fear-based creative about death or illness, prices shown without the conditions behind them, and “no medical exam” claims that apply only to some applicants all create complaints and poor leads. Calm, specific messages about protecting a family’s home, income or plans attract people who are ready to talk and are easier to get through compliance review.
Speed to contact and booking
The first call decides most leads
A person who requests a life insurance quote at lunchtime is often comparing two or three options. The advisor who calls within minutes, introduces themselves clearly and books a proper needs conversation usually wins it; the one who calls the next day often reaches voicemail forever. Lead generation for an advisor has to include how the first contact happens, not just where the lead comes from.
CS+ alerts and booking links
CS+, our CRM, can alert the advisor by text the moment a quote request arrives, send the consumer an immediate confirmation with the advisor’s name, licence details and a link to book a call, and log every attempt. If the advisor is with a client, the consumer can still pick a time. Our insurance CRM for quotes and policies page covers the full pipeline from quote to placed policy and renewal reviews.
AI answering for after-hours enquiries
Many people research life insurance in the evening, after the children are asleep. An AI receptionist for after-hours calls can answer general questions about products and the process, take the person’s preferred time and book a call with the advisor. It should never quote premiums, recommend coverage amounts or collect health details; those belong in the conversation with a licensed advisor.
Nurture for people who are not ready yet
Many life insurance enquiries are early: a couple who will “deal with it after the move”, a parent who wants to talk to their spouse first, a business owner waiting for year-end numbers. A consent-based email nurture keeps the advisor present without pressure: a short series on term versus permanent coverage, what an application involves, how critical illness differs from disability insurance, and a reminder of how to book. Life-event check-ins (a year after a home purchase, at a child’s birth) can bring people back when the need becomes real. Every message follows CASL, with clear sender details and an easy unsubscribe. Our email marketing for advisors builds and runs these sequences, and the content is reviewed by your MGA or brokerage like any other advertising.
Referral and centre-of-influence programs
Professionals who meet your clients first
Mortgage brokers, realtors, accountants, family lawyers, estate planners and financial planners all meet people at the moment insurance becomes relevant. A centre-of-influence program gives each partner a simple way to introduce a client: a short referral page with a form that records the partner’s name, a one-page summary of the products you advise on, and a commitment to follow up quickly and report back (with the client’s consent). Mortgage brokers in particular see the mortgage protection question daily, and our mortgage broker marketing page explains how they find clients, which helps you approach them as a partner.
Client referrals after a policy is placed
A satisfied client who has just finished the application process is the most natural source of the next lead. A thank you message after placement, with a simple way to introduce a sibling, friend or business partner, works better than a generic referral request months later. Any referral incentive must follow the rules that apply to your licence and your MGA’s policy.
Tracking partners
Each referral partner should be tagged in your CRM, so you can see which partners send people who become clients and when you last thanked them.
Group benefits enquiries from employers
Group benefits leads come from a different buyer: a small business owner, an HR manager or an office administrator comparing plans for staff. They search “group benefits for small business”, “employee benefits Ontario” or “group health and dental plan”, and they care about plan design, administration and employee experience. A group benefits page with plan types explained, a quote request that asks for number of employees, province and current plan, and a LinkedIn presence aimed at owners and HR leads fits this buyer. Our B2B marketing for group benefits advisors covers the pages and ads that bring employer enquiries when an advisor wants to grow this line. A group client also opens the door to individual life and disability conversations with the owner and key employees.
Measuring placed policies, not just leads
The numbers that matter
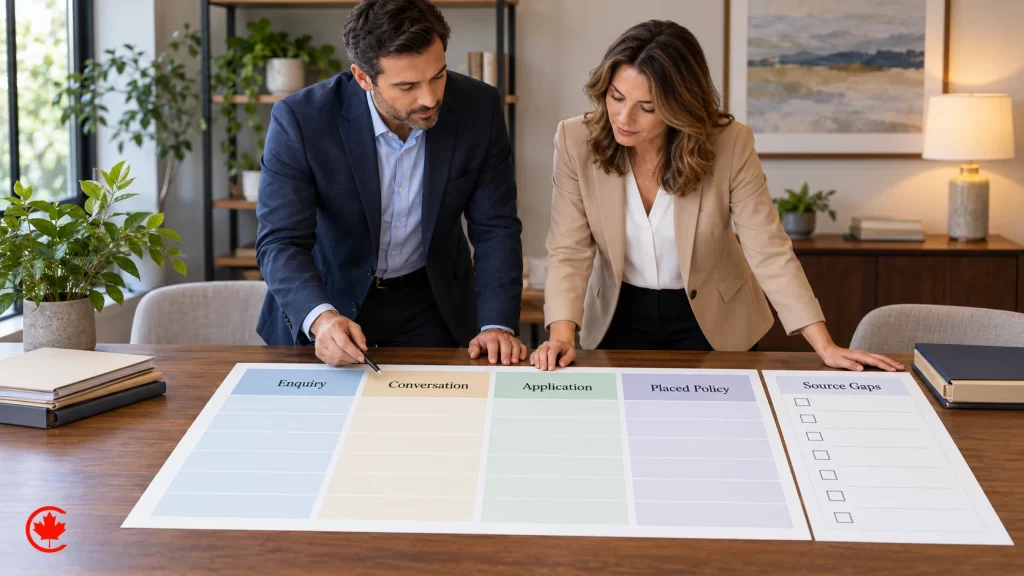
A lead report that counts form fills tells an advisor very little. The useful chain is: enquiries by source and product, first contact time, needs conversations booked, applications submitted, policies placed, and the premium those policies represent, tracked in your CRM. That shows which campaigns, pages and partners bring people who actually become clients, and which bring tyre kickers.
How lead generation fits with the rest
Lead generation is one piece of an advisor’s growth. Brand, website, local presence and the wider insurance marketing plan are covered on our insurance agency marketing page, and the full range of financial work sits on the financial services marketing hub. Our general lead generation services page explains how we build enquiry pipelines across trades. Advisors who also manage investments can look at our CRM for financial advisors, which handles consent-aware follow-up for wealth clients.
Licensing, fair treatment and consent rules for life insurance leads
Licensing and fair treatment
Life insurance advisors must be licensed in each province where they sell, and in Ontario FSRA licenses life agents. Campaigns should only target provinces where you hold a licence. Advertising must not mislead about coverage, premiums or “free” offers, and the Canadian Council of Insurance Regulators and provincial guidance on the fair treatment of customers apply to how products are presented and sold. This is a marketing observation, not legal advice. Your MGA or brokerage compliance team remains the reference for what you may publish.
Health details, consent and calling
No health details go into ad targeting, custom audiences or analytics, and quote forms should collect as little as possible. Commercial email and texts follow CASL, with consent, sender identification and an unsubscribe in every message. Telemarketing calls follow the national do not call list rules, and personal information is handled under PIPEDA or the provincial privacy law that applies. Never promise premiums, approvals or acceptance in any ad or reply.
How we work with advisors and brokerages
We start with a free review of how you get clients today: where enquiries come from, which products they ask about, how fast they are contacted, what your pages and ads say, and how many become placed policies. You receive a custom proposal, with fees quoted in writing and ad spend shown separately. Once you approve it and your MGA or brokerage has reviewed the creative, we build the product pages, quote forms, calculators, campaigns, CS+ alerts and nurture, test every path and launch on agreed milestones. Each month you get a plain report from enquiry to placed policy, by source and product, with the next priorities. Ad accounts, pages, analytics and your contact list are set up in your name or your agency’s name.
What life insurance lead generation costs
Lead generation for life insurance advisors is quoted in writing after the free review. What drives the cost is specific to this work: how many products you want to promote (term, critical illness, disability, final expense and group benefits each need their own page and campaign), how many provinces you are licensed in, whether you want calculators, whether we write the education content and nurture series, the number of advisors who receive leads, and how much compliance review back-and-forth is expected with your MGA. If organic search is added, SEO is quoted in writing too. Ad spend is paid directly to the platforms and shown separately from our fees, and you decide the budget.
An advisor who places mostly term policies for young families needs a different budget from a brokerage running group benefits campaigns for employers across two provinces, and the written quote reflects that difference.
Choosing a life insurance lead partner
Ask anyone offering to generate life insurance leads: Are these leads exclusive to me, and do I own the contact list? How is consent collected, and can I see the exact form wording? Will you send ads and pages to my MGA or brokerage for review before launch? How do you keep health details out of ad targeting and analytics? Do you report placed policies, or only leads? Who owns the accounts? The answer should be you, including the ad accounts, landing pages, analytics and CRM data. Be wary of anyone who promises a fixed number of leads or appointments; no one can promise how many people will need coverage this month.
Book a life insurance lead review and get a custom proposal
Book a free review of your life insurance lead flow. We will look at your sources, pages, first-contact speed and consent wording, and send a custom proposal for leads that you own. Call (416) 273-9030, Monday to Friday, 9 am to 6 pm, and Saturday, 10 am to 2 pm. After hours, our 24/7 AI agent answers the toll-free line, +1 (800) 808-9235, and we’ll follow up the next business morning. You can also reach us through our contact page. We reply within one business day. Advisors and agency principals are welcome at Canada Create, 126 Willowdale Avenue, Suite 3, Toronto.
Talk to a strategist
Ready when you are?
Request a custom proposal
Tell us your goals, budget and timeline. You get a custom proposal and a named strategist, so your next stage of growth starts now.
Review, proposal and launch for life insurance lead campaigns
Plain steps, each in writing, with ad accounts and contact lists in your name.
- Free review First call
We look at your sources, contact speed, consent wording and placed policies.
- Custom proposal Written proposal
Products, pages, campaigns and fees set out in writing.
- Review and launch Agreed milestones
Creative reviewed by your MGA or brokerage, then built, tested and launched.
- Report and adjust Every month
Enquiry to placement reporting by source and product.
Why life insurance advisors choose Canada Create
Since 2008
More than 18 years of websites, search and advertising work for businesses across Canada.
BBB Accredited A+
A BBB Accredited Business with an A+ rating and zero complaints.
Toronto office
126 Willowdale Avenue, Suite 3, Toronto, serving businesses across Canada.
English and French
Our team works in English and French.
Life insurance lead questions
How can a licensed advisor generate life insurance leads of their own?
Build one landing page per product and buyer, such as term for young families, critical illness, disability for the self-employed, final expense and group benefits, each with a short quote request form. Point search and social campaigns at those pages, limited to the provinces where you hold a licence. Referral pages for mortgage brokers, accountants and planners add enquiries from people who already trust the person sending them.
How do you attract people to buy life insurance online?
Meet them at the life event that started the search: a baby on the way, a first home, a marriage or a group plan ending with a job. Most people want a sense of cost and the difference between products before they speak to anyone, and they worry about being oversold. Plain education up front, a needs calculator and the option to pick a time to talk tend to earn more conversations than a free quote form followed by repeated calls.
What does it cost to run life insurance lead generation for an advisor?
It depends on the products you want enquiries for, how many provinces your campaigns cover, and whether you need pages and forms only or also campaigns, nurture emails and a centre-of-influence program. Group benefits work for employers adds its own page and partner tracking. Advisors pick the pieces with us during a free review, then receive the fee as a written quote, with the media budget for your insurance ads paid to Google or Meta on its own.
Does the 5 minute rule matter for life insurance quote requests?
Yes, because someone asking for a quote at lunchtime is often comparing two or three options at once. The advisor who calls within minutes, introduces themselves clearly and books a proper needs conversation usually wins it. CS+ can text you the moment a request arrives and send the consumer a booking link right away, so the first contact happens even during a meeting.
How do live transfer life insurance leads differ from enquiries you generate yourself?
A live transfer connects you to a call that someone else generated, so you rarely know what the person was told or how their consent was collected. When someone fills in a form on your own page after reading about term and permanent coverage, you know the exact wording they saw and which product they asked about. That makes the first call easier and keeps your messaging in line with what your MGA or brokerage approved.
Is buying life insurance leads a sensible way for an advisor to grow?
It can fill a calendar, but shared leads are often sold to several advisors at once, so the consumer gets a flood of calls. Aged leads are older enquiries resold at a lower price, and the flow from any seller ends when you stop paying. Generating your own enquiries builds a list and a source of quote requests that stay with your practice.
How do you generate life insurance leads on Facebook within the rules?
Aim campaigns at life stages such as new parents, homebuyers and business owners rather than health conditions. Meta applies its own financial services and insurance policies and limits some targeting options for these ads, so campaigns have to work within them. Every ad and landing page should also pass your MGA or brokerage review before it runs, and the quick first call matters even more because social forms are easy to forget.
What makes inbound leads for life insurance different from bought lists?
An inbound enquiry comes from someone who found your page and asked you directly, with the consent wording, timestamp and source stored in your CRM. Follow-up emails and texts need consent under CASL, phone follow-up falls under the national do not call list rules, so knowing exactly how consent was given protects your licence. With bought lists you inherit another company's consent practices along with the contacts.
How should an advisor choose a life insurance lead partner?
Look for someone who builds pages and campaigns in your name, records consent on every form, and reports through to placed policies instead of counting form fills. An advisor should also know the firm's street address, scan its current Google reviews, and confirm a compliance review step is part of every launch. Toronto-based since 2008, Canada Create builds that kind of quote request flow for advisors and brokerages across Canada and opens the ad accounts under your practice's name wherever a platform allows it.
Shared leads go to whoever calls first
When a lead is sold to five advisors, the consumer remembers the call that felt least like a sales pitch. Your own pages, fast contact and patient nurture change that. Book a free lead flow review and see where your next clients can come from.