
Toronto · Business loans leads
Business loans leads in Toronto
We build exclusive lead flow for lenders and brokers from your own campaigns, pages and referral partners, qualified before the first call and tracked to funded deals. Fees are quoted in writing.
Lead generation for business lenders, commercial loan brokers, equipment finance and factoring firms: loan type pages, qualifying forms, referral partners and tracking to funded, in Toronto and the GTA and across Canada.
- BBB A+ accredited
- 18 years in business
- Mon to Fri 9 to 6, Sat 10 to 2
Get a custom proposal for your business lending lead
Tell us which loan types you fund or place and the provinces you serve. We reply within one business day.
Please do not share passwords or other sensitive details here. We never sell your contact information and we comply with Canadian privacy law
(privacy policy).
What your lending team gets
Enquiries you can sort
Forms that capture time in business, revenue band, purpose and amount range before the call.
Exclusive lead flow
Enquiries from your own campaigns and partners, never from bought or shared lists.
Faster first contact
Routing and call answering so owners hear from you while they are still deciding.
Funded deals by source
A CS+ pipeline and monthly report from enquiry to funded, on accounts in your name.
What business lending lead generation includes
The pages, forms, channels and tracking a lender or broker needs.
- Loan type landing pagesEquipment, working capital, factoring, commercial real estate, startup and franchise pages.
- Pre qualification formsShort forms with bands for time in business, revenue and amount.
- Search campaignsCampaigns by product and province with negative keywords for consumer searches.
- LinkedIn and emailFollow-up with owners who enquired or are existing clients, with CASL consent records.
- Partner referral programPages and tracked links for accountants, bookkeepers and equipment dealers.
- Lead routing and answeringLeads routed by product, with after hours calls answered and booked.
- Secure document linksClear portal links and reminders for outstanding documents.
- CS+ pipeline and reportingStages from enquiry to funded, with funded deals reported by source.
Pricing for business loans leads, quoted in writing
Fees are quoted in writing after a free review. Ad spend is paid to the platforms and shown separately.
Single product lead flow
Quoted in writing
Lenders or brokers focused on one loan type
- One loan type landing page
- Pre qualification form
- Search campaign
- Lead routing
Multi product program
Quoted in writing
Brokers and lenders with several products
- Pages by loan type
- Campaigns by product and province
- CS+ pipeline to funded
- Monthly funded deal report
Partner and B2B advertising
Quoted in writing
Firms growing referrals and B2B advertising
- Partner pages and tracked links
- LinkedIn campaigns
- CASL compliant email
- Partner updates
Response and answering
Quoted in writing
Teams losing enquiries after hours
- AI call answering
- Instant reply sequences
- Booking into calendars
- Document reminders
Ad spend and software licences are paid to the platform directly and shown separately from our fees.
Business lending lead guide
Business loan enquiries you can actually fund
Business loans leads are enquiries from business owners who want financing and have asked a lender or broker to contact them: a contractor pricing a new excavator, a distributor whose customers pay in sixty days, a franchisee buying a second location, a manufacturer refinancing its building. This page is for business lenders, commercial loan brokers, equipment finance companies, alternative and merchant cash advance lenders, invoice factoring firms and commercial mortgage brokers who want those enquiries from their own campaigns and referral partners, qualified before the first call and tracked through to funding. Canada Create is a Toronto agency with an office at 126 Willowdale Avenue, Suite 3, building lead generation for lenders and brokers across Canada.
- How business owners look for financing
- Landing pages by loan type
- Pre qualification forms that sort enquiries
- Search ads, LinkedIn and email to owners
- Referral partners: accountants, bookkeepers and dealers
- Speed to call and the first conversation
- Secure documents and a CS+ pipeline to funded
- Lead quality, bought lists and funded deals by source
- How lead flow connects to your other marketing
- Lending ad rules, privacy and consent
- How we build a business lending lead program
- What business lending lead generation costs
- Choosing a partner for lender lead generation
- Get a custom proposal for business loan lead generation
How business owners look for financing
What owners search when they need capital
Owners describe the need, not the product a lender files it under. They search for business loans Canada, small business loan Ontario, equipment financing, working capital loan, startup business loan, invoice factoring Toronto, line of credit for a small business or a loan to buy a franchise. Many include their situation: a loan with no collateral, financing for a truck, funding while a large invoice is outstanding. Each search maps to a different product, a different underwriting file and a different lender or broker in your network, and a lead program has to keep them apart from the first click.
Owners who search this way are often under time pressure. A supplier wants a deposit, a piece of equipment is down, payroll is due before a customer pays. They compare two or three lenders or brokers quickly and choose the one that explains its process clearly, asks sensible questions and calls back while they are still at their desk.
What makes an owner choose one lender or broker
Business borrowers weigh the speed of a decision, the documents they will need, how honest the lender is about rates and fees, whether the lender understands their industry and whether a real person will walk them through it. Brokers add a further question: will you shop my file to several lenders and explain the differences? Pages and ads that answer those questions plainly, without promising approval, win the enquiries worth calling.
Searches a business lender should avoid paying for
Many financing searches come from people a business lender cannot help: individuals looking for a small personal loan, a payday advance or a student loan, and people researching government programs with no intention of borrowing privately. Consumer searches about bad credit and debt relief belong to a different kind of provider altogether. A lead program filters these out in the keywords, the ad wording and the first question on the form, so your account managers spend their day on business owners.
Landing pages by loan type
A single apply now page for every product produces mixed, hard to sort enquiries. Lead generation for lenders works better with one landing page per loan type, each written for the owner who needs that product, with its own form and its own tracking.
- Equipment financing and leasing: new and used equipment, vehicles and trucks, with the dealer quote as the starting document.
- Working capital and lines of credit: seasonal gaps, inventory builds and payroll timing, explained without implying a decision before review.
- Invoice factoring and receivables financing: how advances on outstanding invoices work, which customers qualify and what the owner’s customers will see.
- Commercial real estate and commercial mortgages: buying, refinancing or building owner occupied and investment property.
- Startup and franchise financing: what a lender usually needs from a new business, such as a business plan, owner equity and personal credit history, in general terms.
- Merchant cash advances and alternative lending: how repayment works, stated accurately, for owners who need speed over price.
Each page explains who the product suits, what an owner should have ready, what happens after they submit and who will call them. Where a product is a poor fit for some owners, saying so on the page saves your team calls that go nowhere. Pages for brokers also explain that the broker works with several lenders and how the broker is paid, in the terms the broker actually uses.
Pages by kind of business
Where a lender or broker funds certain trades often, a page for that trade within a loan type adds weight: equipment financing for trucking and construction firms, receivables financing for staffing agencies and distributors, working capital for restaurants before patio season, or practice financing for clinics. These pages use the owner’s vocabulary (dump trucks and excavators, net sixty invoices, seasonal inventory) and describe the files you see most, without naming clients or implying outcomes.
Pre qualification forms that sort enquiries
The form is where lead quality is won or lost. A short form with a few qualifying fields gives your underwriters and account managers what they need to prioritize the call list, without asking for anything sensitive before the owner has spoken to a person.
Fields that help a lender sort the queue
- Time in business, in ranges such as under a year or over three years.
- Annual revenue band, chosen from ranges you set.
- Loan purpose: equipment, working capital, real estate, acquisition, startup or other.
- Amount range wanted, again in bands rather than an exact figure.
- Province and type of business, plus the owner’s name, business name, phone and email.
Bands keep the form quick and avoid collecting financial details in a web form. Answers route the lead: a working capital enquiry from a business with two years of revenue goes to one account manager, an equipment enquiry with a dealer quote goes to another, and a pre revenue startup gets an honest reply about which products may fit. Social insurance numbers, bank statements, tax returns and credit details are never asked for on the form; they come later through a secure portal.
Multi step forms
For some products a short multi step form works better than one long page: the owner chooses the loan purpose first, then sees only the questions that matter for that purpose. The final step confirms what happens next and when to expect a call, in the hours your team keeps.
Search ads, LinkedIn and email to owners
Search ads by loan type
Search ads reach owners who are already looking for equipment financing, a working capital loan or factoring. Campaigns are split by product and province, each sending owners to its matching landing page, with negative keywords for personal loan, payday, student loan and job searches so the budget stays on business borrowers. Ad text names the product, the kinds of business you fund and the next step, and states terms only where they are accurate and current. Our Google search ads management covers the platform side.
LinkedIn and email to business owners
LinkedIn reaches owners, controllers and chief financial officers by role, company size and industry, which suits lenders and brokers working with established firms. Useful content works better than a hard pitch: a short guide to what equipment lenders look for, or an explainer on factoring versus a line of credit. Email to business owners follows CASL, with consent or a documented business relationship; our email marketing service sets up permission based lists and sequences, and our B2B marketing team plans ads and pages aimed at the firms you want to fund.
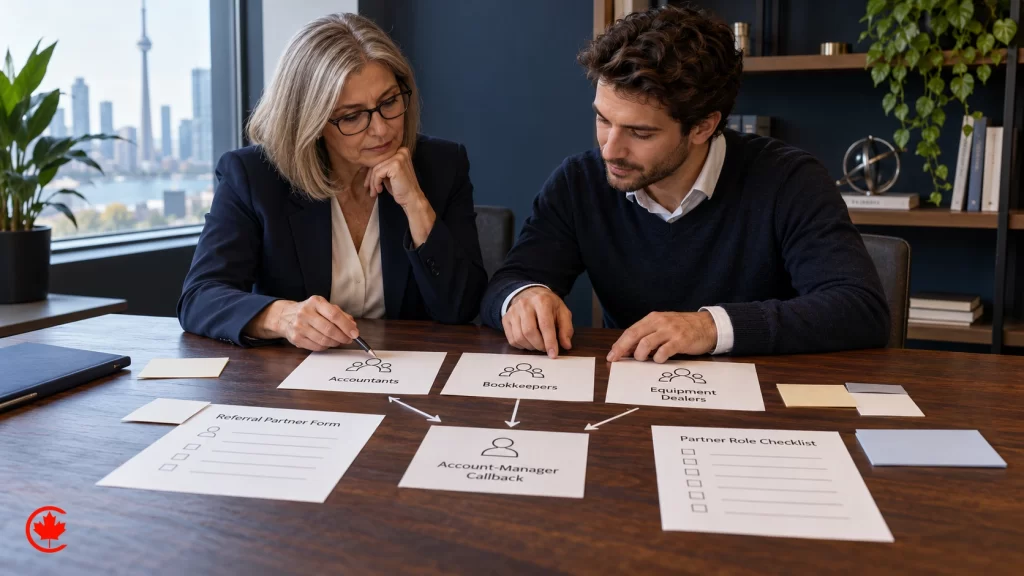
Referral partners: accountants, bookkeepers and dealers
In business lending, the strongest leads often come from people who already know the owner’s numbers. Accountants and bookkeepers see a client’s cash flow problem before the owner calls anyone. Equipment dealers meet the buyer at the moment financing becomes the deciding question. Commercial realtors and business brokers meet owners buying property or a business.
Making referrals simple and trackable
A partner program needs a page for each partner type that explains what you finance and how referred clients are treated, a short referral form or a personal link for each partner so referrals are tracked, and a reply to the partner once the client is contacted. Dealers benefit from a simple quote to financing request they can complete with a buyer on the showroom floor. Accountants and bookkeepers respond to education: short notes on which products suit which client situations. Our marketing for CPA and bookkeeping firms page shows the other side of that relationship. Any referral fees should be disclosed as the rules that apply to you require.
Material partners can pass along
Partners refer more when they have something simple to hand a client. A one page explainer for each product, a short checklist of documents an owner should gather, and a plain note on how long a typical review takes in your own experience give an accountant or dealer confidence to make the introduction. We write these in the partner’s language and keep them consistent with the claims on your landing pages.
Speed to call and the first conversation
An owner who fills in a financing form often fills in two or three. The lender or broker who calls first, with a clear explanation of next steps, usually gets the documents. Speed matters more here than almost anywhere in lead generation, because the owner’s need is often tied to a date.
What the first contact should do
The first reply confirms the enquiry, names the person who will call and says what to prepare. The call itself checks fit using the form answers, explains which products may suit, and sets clear expectations about documents and the review process without suggesting an outcome. When no one can answer, an AI receptionist can take the call, confirm the loan purpose and book a time with an account manager, so an evening enquiry is not lost to a faster competitor.
Secure documents and a CS+ pipeline to funded
Document collection through secure portals
Once the owner wants to proceed, documents follow: financial statements, bank statements, tax filings, equipment quotes, invoices or leases. These move through the secure portal or document system your firm already uses, never through web forms or ordinary email attachments. The website and follow up emails carry a clear link and plain instructions, and CS+ reminds the owner of what is still outstanding without holding the documents itself.
Stages from enquiry to funded
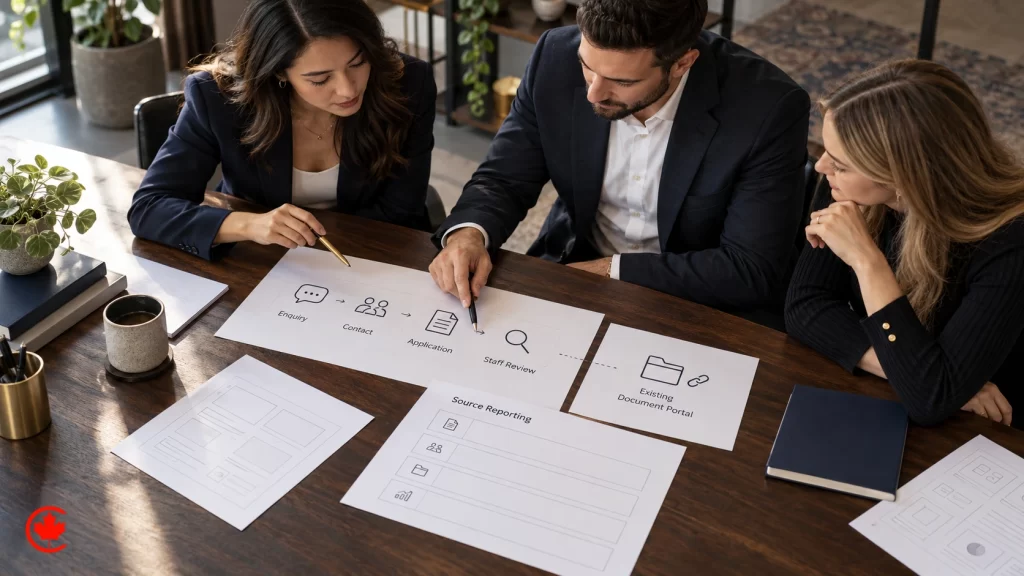
CS+, our CRM, holds each lead from first enquiry through contact, application, documents received, submitted to lender or credit, offer, accepted and funded, with a reason recorded for every deal that falls away. Brokers can see which lender each file went to; lenders can see which account manager is holding it. Tasks and reminders keep files moving, and the pipeline report shows where deals stall. Our CS+ CRM and automation page covers the system; mortgage professionals can also compare our CRM for mortgage brokers.
Lead quality, bought lists and funded deals by source
Why we never buy lead lists
Shared and resold business loan leads reach several lenders at once, often from owners who never asked to hear from you, and lists of business contacts bought for cold email raise consent problems under CASL. Live transfer and aged lead offers carry the same doubts about where the owner came from. We build lead flow from your own campaigns, pages and partners, so every enquiry is exclusive to you and the consent record is clear.
Measuring what matters
Volume is simple to buy and rarely useful. A lender or broker should judge lead generation by applications started, files submitted and deals funded, by source, product and province. A campaign that brings fewer enquiries but more funded equipment deals is worth more than one that fills the queue with pre revenue startups. Monthly reports show those numbers, and budgets move toward the products and sources that fund.
Learning from deals that fall away
Recording why a file did not fund is as useful as counting the ones that did. If many working capital enquiries fall away for time in business, the form and the page should say what you require up front. If equipment files stall waiting for dealer quotes, the partner process needs work. Reasons logged in CS+ turn lost deals into changes to the pages, fields and campaigns.
How lead flow connects to your other marketing
Lead generation for business lending sits inside a wider plan. Our lead generation services page explains the approach across trades, and the financial services marketing hub shows how lending, insurance, advisory and accounting firms fit together. Residential borrowers belong on our residential mortgage leads page, and consumer debt help is a different buyer covered on our Debt Consolidation Advertising page. If your site needs new loan type pages before campaigns start, our website design team builds them.
Lending ad rules, privacy and consent
Accurate terms in ads and pages
Lending ads must state terms accurately. Never say approval is assured or that there is no credit check unless that is strictly true for the product advertised. Provincial consumer protection rules and federal rules on interest apply in general terms, and some products and borrowers fall under them more than others. Google applies financial services ad policies to lending ads, which can require verification and specific disclosures before ads run.
Financial data and consent
Financial data never goes into analytics or ad audiences. Forms collect bands and contact details only, and documents move through secure portals. CASL applies to business email too: consent or a documented business relationship, sender identification and an unsubscribe in every message. PIPEDA sets general duties for the contact data you collect and keep. This is a marketing observation, not legal advice.
How we build a business lending lead program
We begin with a free review of your current enquiry sources, landing pages, forms and how quickly new enquiries are called, plus a conversation about the products you fund or place, your credit appetite and the provinces you serve. You receive a custom proposal covering loan type pages, form fields and routing, campaigns, partner pages, the CS+ pipeline and reporting, with fees quoted in writing.
We build and launch at agreed milestones, then report every month on enquiries, applications, files submitted and funded deals by source. Ad accounts, analytics, landing pages and the CRM are set up in your firm’s name, and ad spend is paid directly to the platforms.
What business lending lead generation costs
Fees are quoted in writing after the free review. What drives the price for a lender or broker: how many loan types and provinces you target, how many landing pages and form versions we write, whether you run search only or add LinkedIn and email, the size of the partner program, French pages, call answering and how deep the CS+ pipeline goes into your underwriting stages. An equipment broker in Ontario with two products needs far less than a lender with six products across several provinces. Ad spend is paid to the platforms and shown separately from our fees; we do not sell leads by the piece.
Choosing a partner for lender lead generation
- Will every lead be exclusive to us, from our own campaigns, with a clear consent record?
- How will forms qualify by time in business, revenue band, purpose and amount without collecting sensitive data?
- How will ad text stay accurate about terms and avoid any suggestion that approval is assured?
- Can you report funded deals by source and product, not just form fills?
- Who owns the accounts? The answer should be you: ad accounts, pages, analytics and CRM in your firm’s name.
- How will referral partners be tracked and thanked?
A partner who asks about your credit box, your underwriting stages and your partner network before talking about lead volume understands how business lending actually funds deals.
Get a custom proposal for business loan lead generation
Tell us which loan types you want more of, the businesses you fund most often and the provinces you serve. A free review looks at your loan pages, your forms, your partner referrals and how fast a new enquiry gets a call, and you receive a custom proposal with fees quoted in writing. Call (416) 273-9030, Monday to Friday, 9 am to 6 pm, and Saturday, 10 am to 2 pm. After hours, our 24/7 AI agent answers the toll-free line, +1 (800) 808-9235, and we’ll follow up the next business morning. You can also reach us through our contact page. We reply within one business day. Canada Create is located at 126 Willowdale Avenue, Suite 3, Toronto, and builds lead flow for lenders and brokers across Canada.
Talk to a strategist
Ready when you are?
Request a custom proposal
Tell us your goals, budget and timeline. You get a custom proposal and a named strategist, so your next stage of growth starts now.
Building a business loans leads program
One plain sequence, starting with a free review of your current enquiry sources.
- Free review First call
Your pages, forms, sources and response speed reviewed with your products and credit appetite.
- Custom proposal Written proposal
Loan type pages, fields, campaigns, partners and pipeline listed, with fees in writing.
- Build and launch Agreed milestones
Pages, forms, routing, CS+ and campaigns built, tested and launched.
- Report and refine Every month
Applications, submissions and funded deals by source, with budgets moved to what funds.
Why lenders and brokers choose Canada Create for business loans leads
Since 2008
More than 18 years of websites, search and advertising work for businesses across Canada.
BBB Accredited A+
A BBB Accredited Business with an A+ rating and zero complaints.
Toronto office
126 Willowdale Avenue, Suite 3, Toronto, serving businesses across Canada.
English and French
Our team works in English and French.
Business loan lead questions
What is a business loan lead?
It is an enquiry from a business owner who wants financing and has asked a lender or broker to contact them, such as a contractor pricing an excavator or a distributor waiting on slow paying customers. Good business loan leads arrive with the loan purpose, time in business and amount range already captured. Canada Create builds that flow from a lender's own campaigns, pages and referral partners.
Is paying for shared business loan leads worth it?
Shared or resold enquiries often reach several lenders at once, which makes the first call a race and the data hard to trust. Enquiries generated by your own campaigns and partners go to nobody else, and each one can be followed to a funded deal. Judging any source by funded deals rather than by the number of enquiries shows what each one is really worth.
How should a lender's website explain how hard it is to get a small business loan?
Each loan type page should say who the product suits, what an owner should have ready and what happens after they submit, all in general terms. Where a product is a poor fit for some owners, saying so saves your team calls that go nowhere. Pages should never imply a decision before the file has been reviewed.
Should a business loan pre qualification form ask for a credit score?
No, the web form should stay short and avoid sensitive financial details. Bands for time in business, annual revenue, loan purpose and amount range give underwriters enough to sort the queue. Social insurance numbers, bank statements, tax returns and credit details come later through a secure portal.
Can business lending ads quote current commercial loan rates?
Only when the terms are accurate, current and shown with the conditions that apply. Ad text works best when it names the product, the kinds of business you fund and the next step, without promising approval. If rates change often, keep them on the landing page where they can be updated in one place.
What does business loan lead generation cost in Canada?
Fees depend on how many loan types and provinces you want enquiries for, whether a partner referral program is included and whether after hours call answering is part of the setup. Lenders pay the ad platforms for clicks themselves, apart from our fee. Canada Create sets out the lender lead fee in writing after looking at how your business loan enquiries arrive today.
How do lenders get more business loan leads from referral partners?
Give accountants, bookkeepers and equipment dealers their own partner pages and tracked links, so every referral is recorded with its source. Partners keep sending owners when they see their clients are called back promptly and treated well. Reporting funded deals by partner shows which relationships deserve more attention.
Why does call speed matter so much with business loan leads?
Owners looking for financing are often under time pressure, with a supplier deposit due or equipment down, and they compare two or three lenders quickly. The lender who calls back while the owner is still at their desk usually gets the conversation. Routing by product and answering after hours calls keep those enquiries from going cold.
How should a lender choose a business loan leads provider?
Ask where the enquiries come from, whether they are exclusive to you and whether the provider reports funded deals by source rather than clicks. Ad accounts, landing pages and the CRM pipeline ought to belong to the lender. Canada Create builds lender lead programs for business finance firms across Canada and answers every enquiry within one business day.
Is your team calling enquiries that never fund?
One apply now form for every product fills the queue with mixed, unqualified enquiries. Loan type pages and short qualifying forms put the right files in front of the right people. Ask for a free lead generation review.